
The NOI formula for commercial real estate is effective gross income minus operating expenses. Calculate recurring, collectible property income first, subtract the recurring costs required to run the property, and keep loan payments, income taxes, depreciation, and major capital work separate from the standard NOI calculation.
Key takeaways
- Net operating income, or NOI, measures property income after operating expenses and before debt service, income taxes, and depreciation.
- A practical NOI calculation starts with potential rent, subtracts vacancy, concessions, and credit loss, then adds recurring other income before expenses.
- Lenders may normalize vacancy, management fees, reserves, insurance, taxes, and unusual income rather than accept an owner’s trailing statement unchanged.
- Fannie Mae’s August 2024 multifamily reporting definitions calculate NOI as effective gross income minus total operating expenses, then calculate net cash flow after deducting replacement reserves.
- A strong loan submission reconciles the owner’s actual NOI to the lender’s underwritten cash-flow figure line by line.
NOI is easy to state and easy to misstate. The formula matters, but so do the definitions behind each income and expense line, especially when a purchase or refinance depends on how a lender underwrites the property’s cash flow.
What is the NOI formula in real estate?
NOI in real estate shows the income a property produces after normal operating expenses. It is a property-level measure, so it does not subtract mortgage principal, mortgage interest, investor income taxes, or depreciation.
The compact formula is:
“text NOI = Effective Gross Income − Operating Expenses “
For a typical income-producing property, effective gross income begins with potential rent, subtracts vacancy, concessions, and unpaid rent or credit loss, then adds recurring income such as parking, laundry, storage, or reimbursements where applicable. Operating expenses can include property taxes, insurance, utilities paid by the owner, repairs and maintenance, payroll, management, marketing, and administration.
NOI can also support a valuation discussion: cap rate = NOI ÷ property value. The income definition and the cap rate convention must match, however. Capitalizing an NOI that omits a recurring cost can overstate value.
The useful version of NOI is not the highest possible number. It is the recurring income the property can support after the costs required to operate it.
Why might a lender's NOI be lower than the owner's NOI?
A lender may adjust an owner's income statement to estimate stabilized, repeatable property performance. That does not automatically mean the owner's records are wrong; it means underwriting tests whether the reported result is likely to continue through the loan term.
Here are four adjustments worth reconciling before submitting financials:
- Vacancy, concessions, and credit loss. A property can show high physical occupancy while still collecting less than its potential rent because of concessions, delinquency, or other economic loss. The Fannie Mae Multifamily Guide says underwritten economic vacancy should be supported by current data and three years of historical economic-vacancy data. Fannie Mae's Underwritten NCF guidance illustrates why a single strong month is rarely enough for underwriting. (mfguide.fanniemae.com)
- Management fees. Self-management does not necessarily make management cost disappear in a lender's normalized view. Fannie Mae's August 2024 multifamily reporting definitions allow a normalized management fee based on the underwritten fee, actual fee, or 3% to 5% of effective gross income, and generally set a 3% floor subject to stated exceptions. Fannie Mae Form 4254.DEF is specific to its multifamily reporting framework, not a universal quote for every lender or asset type. (multifamily.fanniemae.com)
- Replacement reserves. A standard NOI presentation may stop before replacement reserves, while a lender's cash-flow test may continue past NOI. In the same Fannie Mae form, NOI equals effective gross income less total operating expenses, while net cash flow deducts replacement reserves after NOI. If an underwritten reserve is unavailable and the escrow is waived, the form specifies annual reserves of $250 per non-senior-housing unit or $300 per senior-housing unit. (multifamily.fanniemae.com)
- Nonrecurring income. A reimbursement tied to the current period can be meaningful, but a gain on sale, insurance proceeds, interest income, prior-period tax reimbursement, or a temporary payment is not the same as recurring operating income. Fannie Mae's form specifically lists several items to omit from other income, including gain on sale and insurance proceeds, with a stated exception for rent-loss insurance proceeds in gross potential rent. (multifamily.fanniemae.com)
Before an application, compare your property statement with what lenders review before approving a commercial loan. The goal is not to force your NOI into one template. The goal is to explain every material difference before an underwriter has to ask.
A lender-adjusted NOI should be traceable back to the owner's operating statement, with each normalization explained and supported.
How do you calculate NOI step by step?
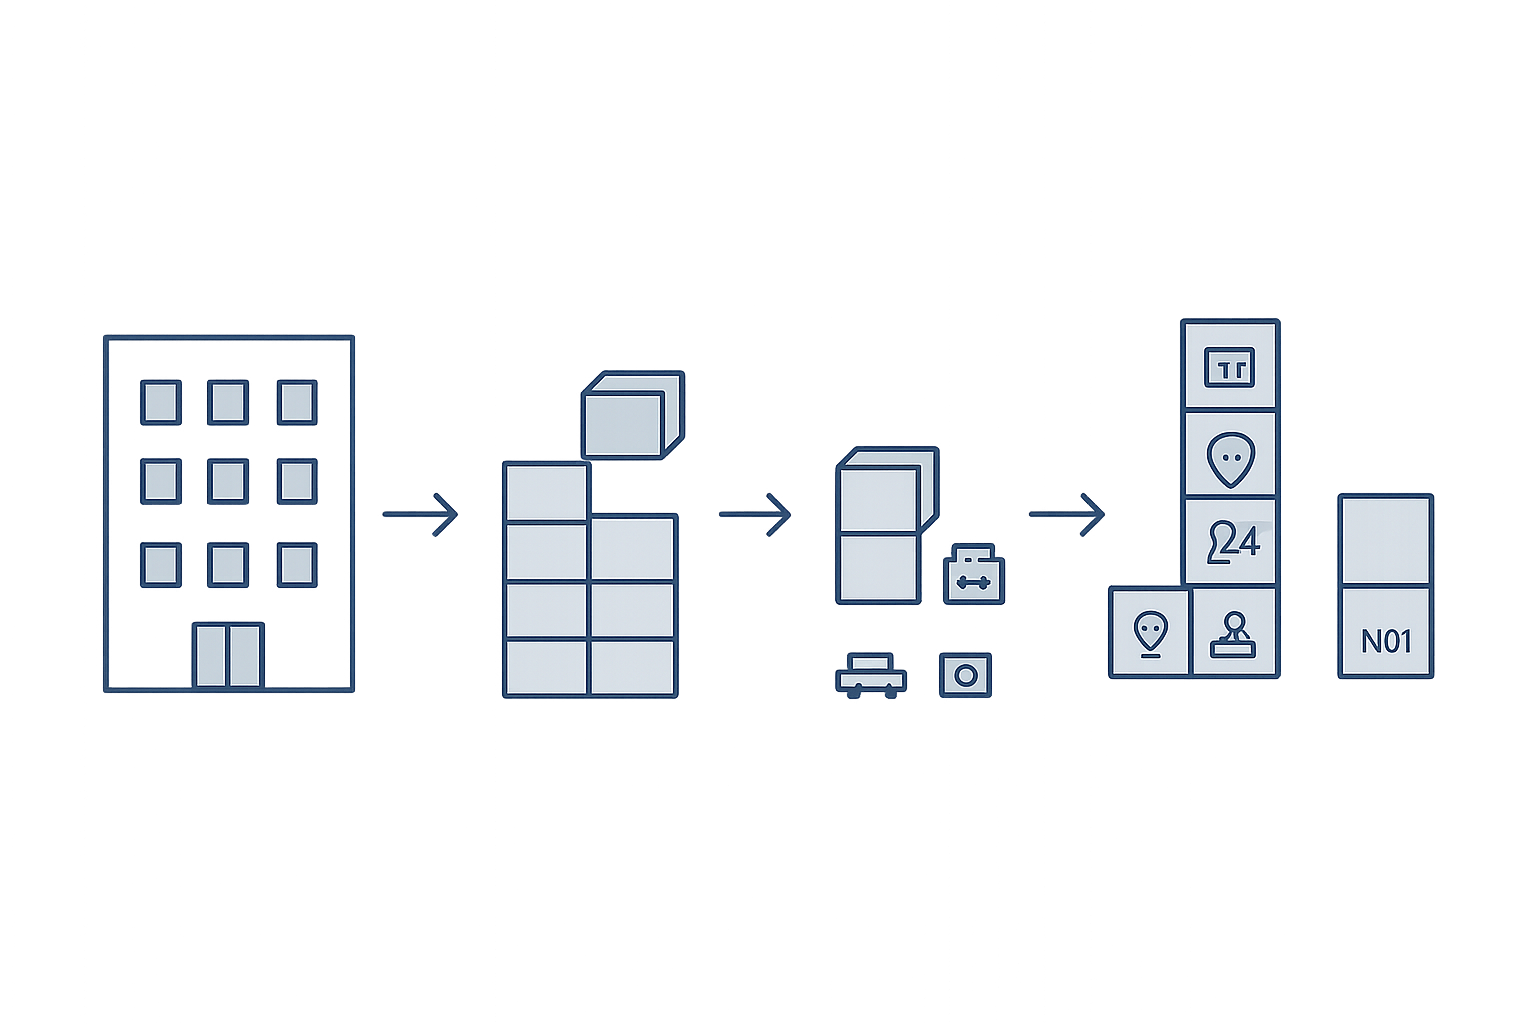
Calculate NOI by moving from potential income to collectible income, then subtracting recurring operating costs. Use a trailing 12-month statement when possible, because it captures seasonality and one-off items better than a single month.
Use this sequence:
- Start with potential gross rental income. In this example, annual scheduled rent is $600,000.
- Subtract economic loss. Assume $18,000 of vacancy and concessions plus $12,000 of credit loss. Potential rent after these losses is $570,000.
- Add recurring other income. If parking and laundry income total $15,000, effective gross income is $585,000.
- Subtract operating expenses. Assume taxes, insurance, payroll, repairs, utilities, management, and administrative costs total $215,000.
“text Potential rent $600,000 Less: vacancy, concessions, credit loss ($30,000) Plus: recurring other income $15,000 Effective gross income $585,000 Less: operating expenses ($215,000) NOI $370,000 “
This illustrative property has $370,000 of NOI. If the lender separately requires $25,000 of annual replacement reserves, cash flow after that reserve is $345,000, not $370,000. That difference can matter when a lender evaluates debt-service coverage.
For an apartment acquisition, the same discipline applies to rent rolls, concessions, bad debt, and property expenses. See this guide to financing multifamily acquisitions for the financing questions that follow the property-level calculation.
Calculate NOI from recurring operations, then show reserves and debt service separately so each user can see which cash-flow measure is being discussed.
Which items belong in NOI and which do not?
Operating costs belong in NOI when they are recurring expenses necessary to run the property. Financing costs, income taxes, depreciation, and major capital improvements are normally kept outside the standard NOI formula.
A practical sorting rule is to ask: Would this cost still exist if the property had no mortgage and kept operating in its current use? If yes, it is more likely an operating expense. Property taxes, insurance, repairs, utilities, onsite payroll, cleaning, management, leasing, and ordinary administration generally pass that test.
Items usually outside standard NOI include:
- Mortgage principal and interest
- Investor or entity income taxes
- Depreciation and amortization
- Acquisition costs and loan fees
- Major improvements, such as a new roof or a whole-building system replacement
- One-time legal settlements or insurance recoveries
The tax treatment of an item is not the same as its NOI treatment. The IRS lists mortgage interest and depreciation among rental-property deductions, while Fannie Mae's operating statement form calculates NOI from effective gross income less operating expenses. Those calculations answer different questions. IRS Publication 527 for 2025 explains rental income and tax deductions; it should not be used as a substitute for a lender's underwriting template. (irs.gov)
A capital item should not be hidden in repairs merely to make NOI look stronger. Buyers evaluating a property should also understand how the calculation fits into commercial property financing decisions.
Consistent classification is more valuable than an aggressive classification, because lenders, buyers, appraisers, and investors need to compare like with like.
Is NOI calculated monthly or yearly?
NOI can be calculated monthly, quarterly, or annually, as long as income and expenses cover the same period. Annual NOI is most useful for valuations, cap-rate analysis, and many loan-sizing conversations because it reflects a full operating cycle.
For example, if a property has monthly effective gross income of $48,750 and monthly operating expenses of $17,917, monthly NOI is $30,833. Multiplying by 12 gives approximately $370,000 of annual NOI, assuming the monthly figures are representative.
Fannie Mae's reporting definitions require operating data and debt service to reflect the same reporting period and describe quarterly and annual reporting periods. That matching principle applies to any useful NOI calculation. (multifamily.fanniemae.com)
Use a monthly NOI to monitor operations, but use a complete and reconciled period when making a valuation or financing decision.
Is NOI the same as EBITDA?
No. NOI is a property-level real estate metric, while EBITDA is a company-level, non-GAAP earnings measure based on earnings before interest, taxes, depreciation, and amortization.
The U.S. Securities and Exchange Commission describes EBITDA as earnings before interest, taxes, depreciation, and amortization, and notes that measures calculated differently should be labeled differently, such as adjusted EBITDA. A property owner's EBITDA can include entity-level income and overhead that are not part of a specific building's NOI. The SEC's non-GAAP financial-measures guidance explains the distinction. (sec.gov)
NOI helps assess property operations; EBITDA helps assess a business or entity. Treating them as interchangeable can distort both analyses.
What else do investors ask about the NOI formula?
The questions below use the language searchers commonly use when comparing property income, valuation, and financing. The answers are short, but each requires the same underlying discipline: define the period, classify each line item consistently, and separate recurring operations from capital and debt costs.
Is noi the same as ebitda?
No. NOI measures the operating income of a specific income-producing property after property operating expenses, while EBITDA is a company-level non-GAAP earnings measure before interest, taxes, depreciation, and amortization. A real estate business may report both, but they use different income, expense, and entity-level assumptions. (sec.gov)
What is a good noi percentage?
There is no universal good NOI percentage. Investors sometimes calculate NOI margin as NOI divided by effective gross income, but a useful result depends on property type, age, location, lease structure, utilities, taxes, insurance, deferred maintenance, and the risk assumed in the projected income. Compare similar properties using the same expense conventions.
What is the 2% rule for rentals?
The 2% rule is a quick rental-property screening heuristic, not an NOI formula or a lender underwriting standard. It generally compares monthly rent with the purchase price, but it does not account for vacancy, taxes, insurance, maintenance, management, capital expenditures, financing costs, or local operating conditions that determine actual NOI.
Is noi calculated monthly or yearly?
NOI can be calculated monthly or yearly if the income and expenses use the same period. Monthly NOI helps track current operations, while annual or trailing-12-month NOI is generally more useful for evaluating seasonality, property value, and loan underwriting because it captures a more complete operating period.
The right NOI period is the one that matches the decision being made and can be supported by complete property records.
What should you bring to a lender?
Bring the operating statement, rent roll, lease summary where relevant, tax bills, insurance information, management agreement, explanation of vacancy and concessions, and a list of unusual income or expenses. If there is a recent renovation, provide the scope, cost, completion date, and evidence of whether the work is recurring maintenance or capital improvement.
A lender-ready package makes it easier to compare actual NOI, stabilized NOI, reserve deductions, and debt service without losing the story behind the numbers. For help connecting that analysis to a debt strategy, request a commercial financing discussion with Thorne CRE.
The best next step is to reconcile the property's reported NOI to a conservative underwriting version before you ask a lender to size the loan.