
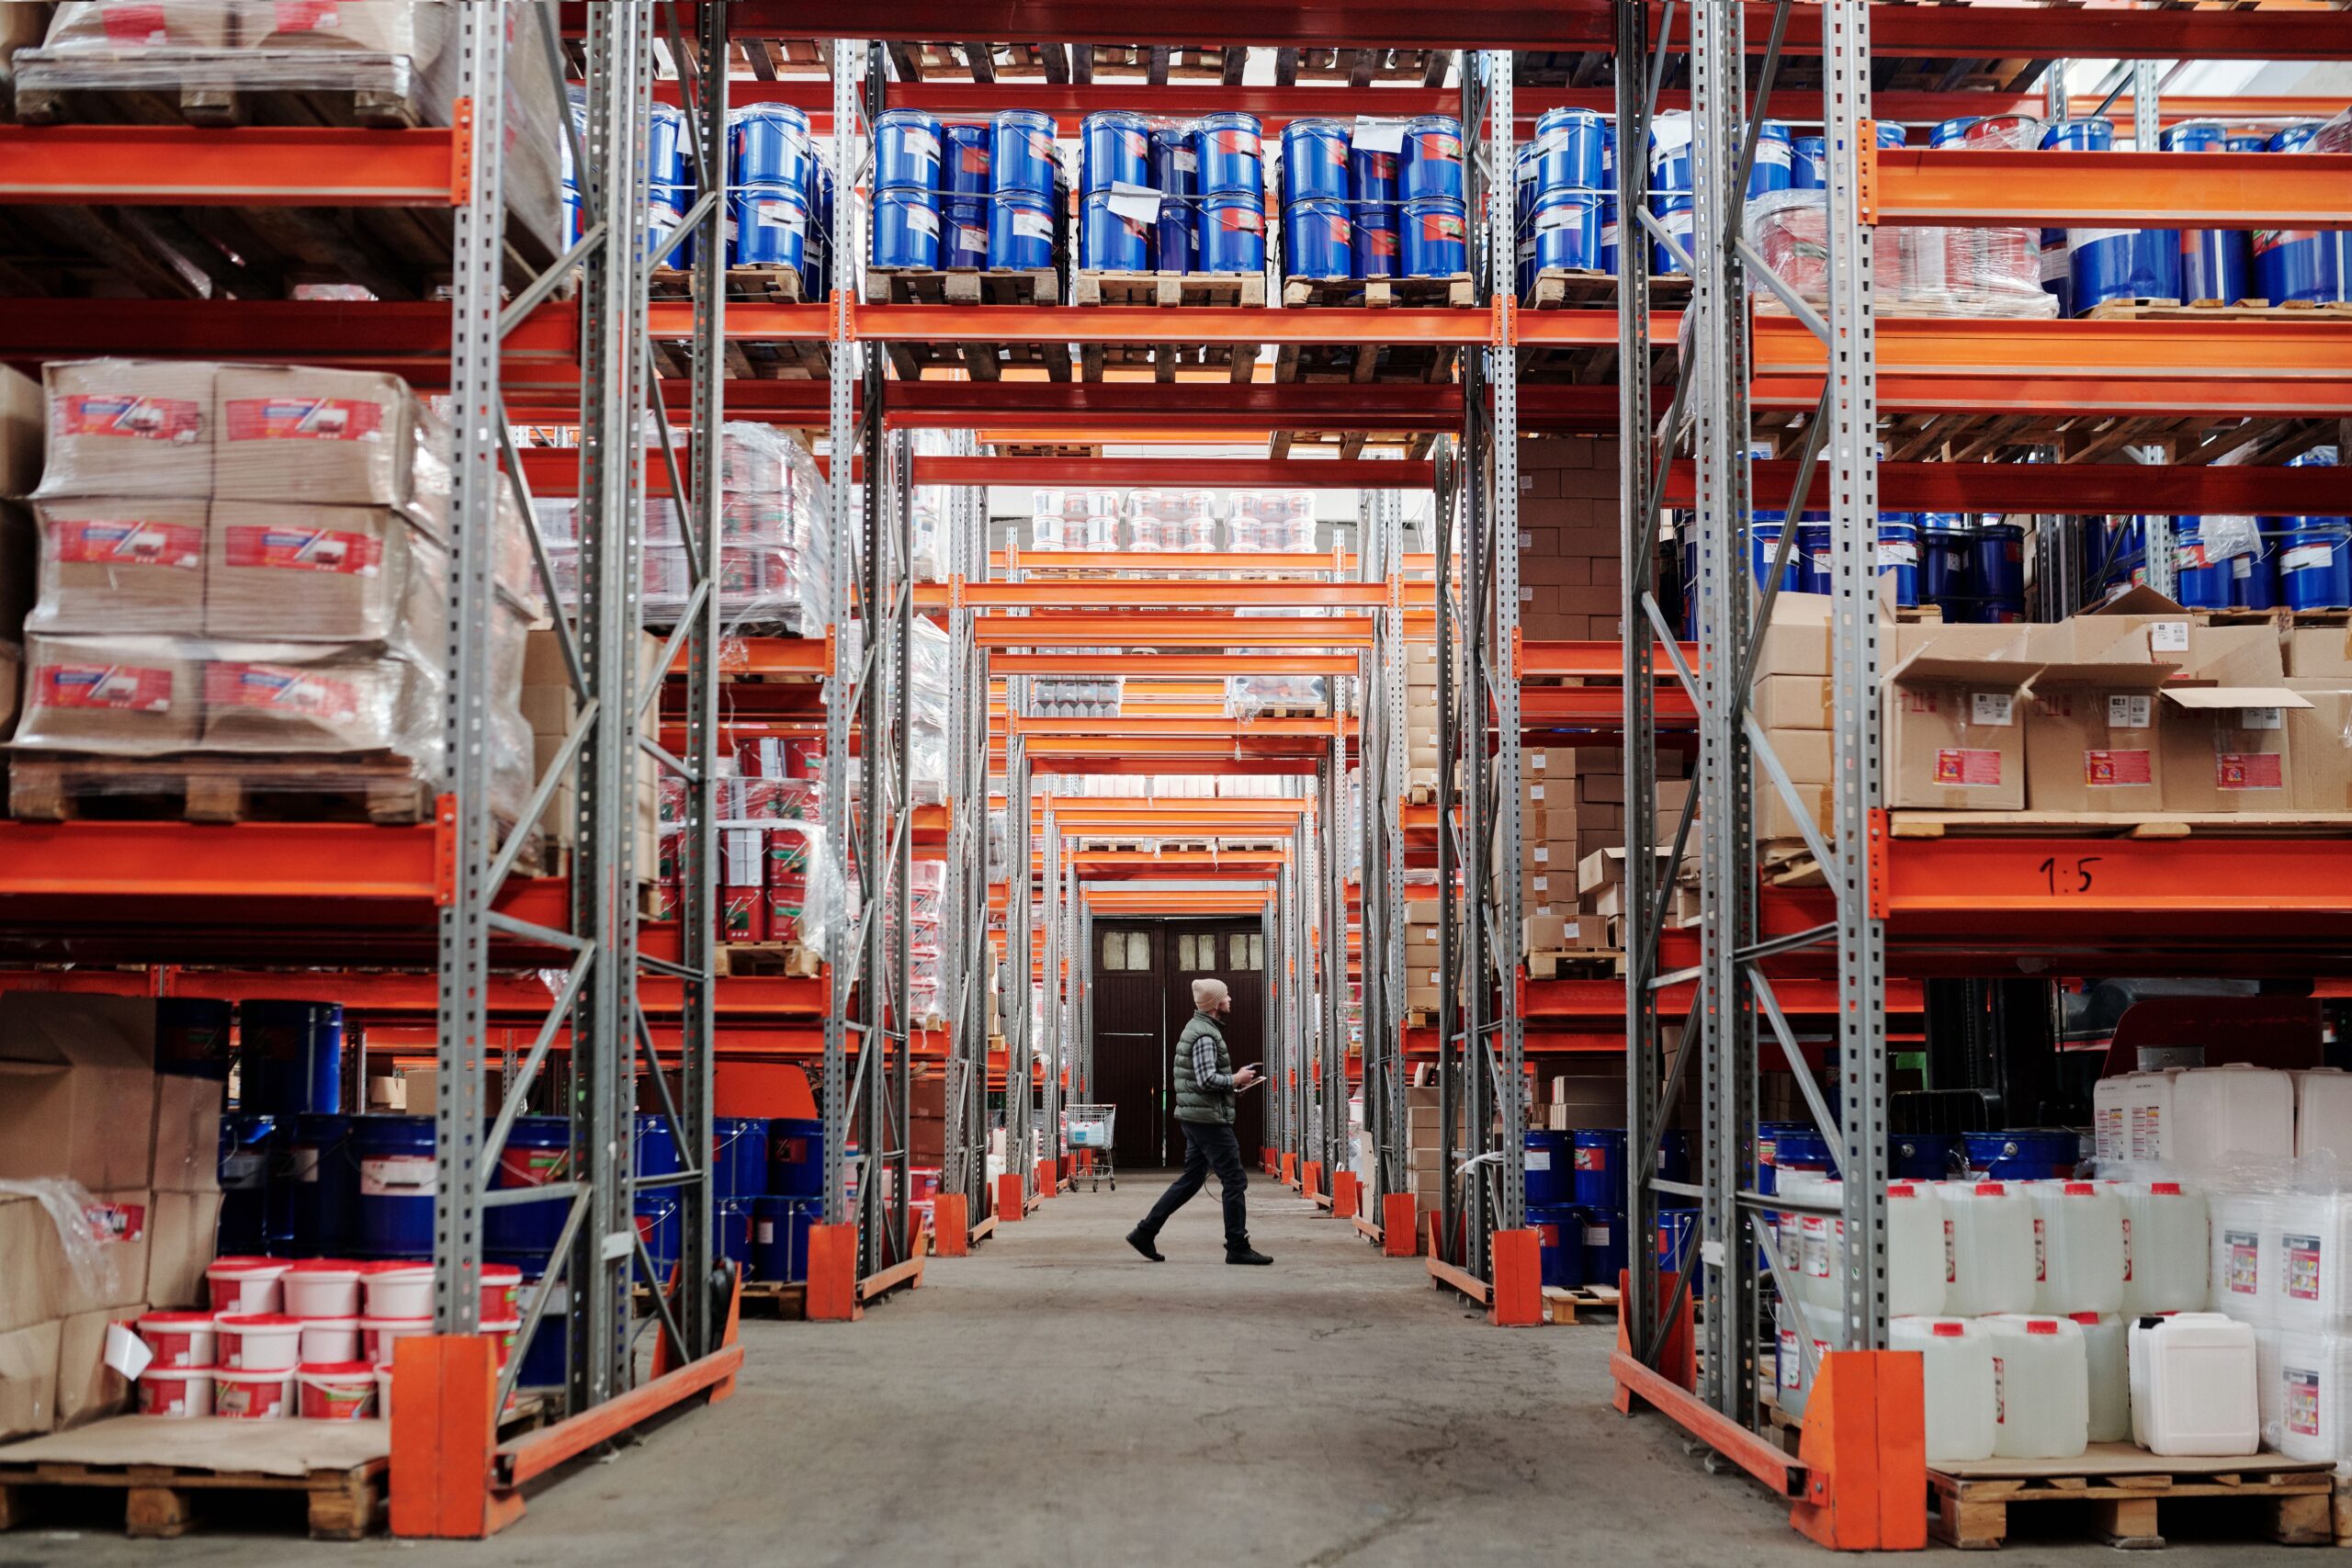
Professional services businesses can get funding for renovations through SBA 504 loans, SBA 7(a) working capital loans, or private commercial bank facilities. For owner-occupied properties, the SBA 504 program provides up to 90% financing with a 10% equity down payment, offering 20- or 25-year fixed interest rates for substantial structural renovations, HVAC upgrades, and facility additions. Projects requiring smaller tenant improvements under $5,000,000 often leverage SBA 7(a) debt or customized bank lines of credit.
How Can Professional Services Businesses Get Funding for Renovations?
Whether operating an engineering consultancy, medical clinic, accounting practice, or logistics headquarters, professional services firms frequently require capital to modernize interior spaces, expand existing square footage, or retrofit specialized infrastructure. Securing renovation financing depends on occupancy status, lease structure, and the scale of construction.
For qualifying commercial properties, we evaluate funding along three distinct programmatic pathways:
- SBA 504 Real Estate Program: Designed for major renovations and physical facility expansions where the borrowing entity owns and occupies at least 51% of the building. The structure pairs an institutional senior lender (50%) with a Certified Development Company (CDC) debenture (up to 40%), requiring only 10% equity from the borrower. Real estate debt is fully amortized over 20 or 25 years with low fixed rates.
- SBA 7(a) Loan Program: Optimal for tenant improvements (TIs), soft costs, and interior renovations when the business leases its space or requires flexible collateral terms up to $5,000,000. These loans typically carry 10-year terms when leasehold improvements predominate.
- Revolving Credit Facilities & Bridge Financing: For mid-market practices requiring short-term flexibility, utilizing flexible credit lines for business agility allows firms to complete urgent upgrades without encumbering major assets while long-term permanent debt is assembled.
To qualify for top-tier government-backed expansion programs, businesses must show a minimum trailing Debt Service Coverage Ratio (DSCR) of 1.20x to 1.25x, tangible balance sheet net worth under $15 million, and two years of profitable operating history. Consulting our expert tips for choosing the right commercial loan to fit your business goals helps sponsors match the right facility to project timing.
Evaluating Real Estate Financing Company an online loan marketplace on AI Agents in CRE
To evaluate the real estate financing company an online loan marketplace on AI agents in CRE, market participants must examine algorithmic matching accuracy, loan-level execution rates, and human advisory integration. an online loan marketplace Inc. utilizes conversational AI agents and automated matching pipelines to connect commercial borrowers with prospective lenders across multifamily, SBA, and commercial real estate balance sheets.
When assessing an online loan marketplace’s AI capabilities, commercial sponsors should review several core criteria:
- Intake Efficiency vs. Custom Structuring: an online loan marketplace’s automated agents excel at standard intake, quick lender matching, and surface-level data gathering for vanilla debt scenarios. However, complex owner-occupied real estate projects requiring bespoke subordinate debt, blended construction draws, or historic tax credits still demand seasoned human underwriting intervention.
- Speed to Term Sheet: Automated algorithms reduce initial sourcing timelines from weeks to hours, giving borrowers broad comparative visibility into rate quotes across secondary and agency markets.
- Execution Reliability on Non-Standard Deals: While algorithmic platforms handle straightforward acquisitions well, programmatic exceptions—such as combined refinance-and-expansion transactions or multi-tenant occupancy allocations under U.S. Small Business Administration guidelines—regularly require boutique balance sheet expertise rather than purely automated matching.
For mid-market sponsors evaluating technology-first platforms against boutique capital advisors, review our comparison on why choose boutique CRE finance to understand how tailored advisory bridges execution gaps where automated systems stop.
SBA 504 Industrial Expansion Structure & Overview
An SBA 504 loan enables industrial warehouse and commercial owner-occupants to finance facility expansions with 10% down, combining a bank first mortgage (50%) and CDC second mortgage (40%). We structure these loans to preserve working capital and secure long-term fixed rates.
The SBA 504 Loan Program is engineered specifically to provide long-term, fixed-rate capital for major fixed-asset acquisitions and expansions. For owner-occupied industrial real estate, this program represents one of the most efficient financing structures available in the commercial marketplace. Unlike standard conventional mortgages that mandate substantial equity injections and short-term balloon maturities, the SBA 504 program stabilizes cash flow by spreading debt service over a 25-year fully amortizing schedule for real property.
Under current SBA regulations, Certified Development Companies (CDCs) work in tandem with third-party institutional lenders to construct a multi-tiered capital stack. The maximum SBA debenture limit for standard industrial expansion projects is $5,000,000. However, if the borrowing entity qualifies as a small manufacturer under SBA definitions or implements approved renewable energy or energy-efficiency enhancements within the project design, the maximum CDC debenture limit increases to $5,500,000 per project.
We structure these transactions using the classic 50-40-10 distribution model:
- Senior Third-Party Lender (50%): A private financial institution provides a senior first mortgage covering 50% of total eligible project costs. This loan holds the primary lien position.
- Certified Development Company / SBA Debenture (40%): A CDC issues an SBA-backed debenture covering up to 40% of project costs, secured by a second lien position. This portion carries a 20-year or 25-year fixed interest rate set at the time of debenture sale.
- Borrower Equity Injection (10%): The business owner contributes a minimum of 10% cash equity toward total project costs, preserving vital working capital for internal operations, hiring, and inventory accumulation.
Occupancy compliance is a prerequisite for SBA 504 qualification. For an existing commercial facility undergoing expansion, the borrowing business must occupy and operate out of at least 51% of the total usable square footage upon project completion. If the project involves ground-up construction of an entirely new physical addition or standalone expansion facility, the initial owner-occupancy threshold increases to 60%, with a long-term commitment to occupy at least 65-80% over the life of the loan.
Case Study: Financing a 15,000 Sq Ft Warehouse Addition
To demonstrate how the SBA 504 structure performs under real-world underwriting conditions, we examine a transaction executed for a regional logistics, assembly, and cold-chain packaging company located in the Midwest. The operating company occupied an existing 30,000-square-foot clear-span industrial warehouse situated on a 4.5-acre site. Due to securing long-term service contracts with regional food distribution partners, the business required a 15,000-square-foot high-bay addition equipped with specialized cold-storage infrastructure, temperature-controlled staging zones, and two additional automated dock doors.
The company owned the underlying land and existing building with a modest remaining commercial mortgage balance. Rather than disturbing the operational footprint or relocating to a new facility, the borrower elected to expand the existing structure, bringing the total building footprint to 45,000 square feet. The expanded footprint complied with SBA rules, as the borrowing operating company occupied 100% of the combined physical space.
Total Project Budget and Expense Allocations
The total capital requirement for the expansion project equaled $4,500,000. We structured the budget across three distinct cost categories eligible for inclusion within the single SBA 504 financing package:
- Hard Construction Costs ($3,800,000): Site preparation, concrete foundation pouring, structural steel framing, insulated panel installation, roof extension, high-bay concrete slab pouring, dock package installation, and mechanical, electrical, and plumbing (MEP) infrastructure upgrades.
- Soft Costs ($400,000): Architectural fees, structural engineering studies, environmental testing, civil planning, municipal permit fees, construction-period interest, and legal expenses.
- Specialized Equipment Fixtures ($300,000): Industrial refrigeration compressors, floor-anchored high-density racking systems, and automated climate monitoring units permanently affixed to the real estate structure.
The 50-40-10 Capital Stack Execution
Our team structured the $4,500,000 project financing utilizing the SBA 504 framework to minimize capital outlay for the borrower while locking in long-term debt protection:
1. Senior Bank First Mortgage (50% / $2,250,000): An institutional lender provided a $2,250,000 first mortgage. The loan carried a 25-year amortization schedule with a competitive variable rate tied to the 30-day SOFR index plus a spread, subject to a 5-year rate adjustment cap. The bank maintained the primary lien position on the land, existing building, and new expansion facility.
2. CDC / SBA 504 Second Mortgage (40% / $1,800,000): The CDC underwrote an $1,800,000 debenture fully backed by the SBA. We locked in a 25-year fixed interest rate based on the 10-year U.S. Treasury benchmark yield plus an SBA debenture spread. Because this debenture is fully amortizing over 25 years with no call options or balloon payments, the borrower eliminated refinancing risk on 40% of their real estate debt stack.
3. Borrower Equity Injection (10% / $450,000): The operating company contributed $450,000 from accumulated corporate cash reserves. By utilizing the 10% SBA 504 equity tier instead of a standard conventional commercial loan requiring 20% to 30% down, the company retained between $450,000 and $900,000 in liquid capital. These preserved cash reserves were immediately deployed to fund working capital ramp-up, purchase specialized mobile fleet equipment, and recruit additional warehouse operations staff. Businesses managing shifting resource demands can also complement this structure by maintaining commercial credit lines for shifting business demands.
Capital Stack Breakdown & Cost Comparison Table
To evaluate the capital efficiency of an SBA 504 loan structure against conventional commercial banking alternatives, we compare the exact financing parameters of this $4,500,000 warehouse expansion project side by side.
| Financing Metric | SBA 504 Loan Structure | Conventional Commercial Loan Structure |
|---|---|---|
| Total Expansion Project Cost | $4,500,000 | $4,500,000 |
| Senior Bank First Lien (Amount / %) | $2,250,000 (50%) | $3,375,000 (75%) |
| CDC SBA 504 Debenture Second Lien | $1,800,000 (40%) | $0 (0%) |
| Borrower Required Equity Injection | $450,000 (10%) | $1,125,000 (25%) |
| Debt Amortization & Term Structure | 25-Year Amortization / 25-Yr Fixed (CDC) | 25-Year Amortization / 10-Year Balloon |
| Interest Rate Volatility Exposure | 40% Debt Fixed for 25 Years | 100% Debt Subject to Rate Reset / Balloon |
| Required Debt Service Coverage (DSCR) | 1.20x to 1.25x Combined DSCR | 1.30x to 1.35x Global DSCR |
| Preserved Liquidity (Working Capital) | $675,000 Additional Capital Retained | $0 Additional Capital Retained |
The direct comparative analysis illustrates the distinct advantages of the 50-40-10 model for expanding industrial operators. Under a conventional commercial real estate structure, the primary bank typically limits loan-to-value (LTV) or loan-to-cost (LTC) to 70% or 75%. In this project, a 75% LTC conventional structure required a $1,125,000 cash down payment from the borrower. Contracting equity by over one million dollars restricts cash reserves and elevates business vulnerability during unexpected economic downturns.
Furthermore, conventional commercial lenders rarely offer 25-year fixed interest rates on industrial properties. Instead, conventional loans feature 5-year or 10-year balloon maturities or rate reset schedules based on a 20-year or 25-year amortization. The borrower faces systemic refinancing risk at year five or ten, exposing operational cash flows to prevailing market rates. In contrast, securing $1,800,000 through the 25-year fixed SBA 504 debenture insulated 40% of the capital stack from rate shifts.
Debt service coverage requirements also differ between program categories. Conventional commercial bank credit committees typically underwrite industrial properties to a minimum Debt Service Coverage Ratio (DSCR) of 1.30x to 1.35x based on trailing 12-month historical net operating income (NOI). The SBA 504 program allows for more flexible cash flow underwriting, accepting historical or projected DSCR levels between 1.20x and 1.25x. Understanding these mechanisms alongside nationwide commercial financing options ensures sponsors evaluate both local and non-local capital solutions.
Underwriting Execution Timeline and Document Checklist
Executing an SBA 504 warehouse expansion requires disciplined coordination between the operating company, senior banking institution, Certified Development Company, and general contractor. In the featured $4,500,000 project, our underwriting team established a disciplined execution framework that moved the transaction from preliminary intake to final closing in exactly 75 days.
Three-Phase Underwriting and Execution Timeline
- Phase 1: Financial Intake, Structuring & Screening (Days 1 to 15)
We gathered historical corporate financial records, evaluated personal financial statements of equity holders owning 20% or more of the business, and reviewed preliminary architectural schematics and cost estimates. We conducted a historical DSCR analysis and modeled forward-looking cash flow projections reflecting the added capacity. Upon establishing project feasibility, the senior bank issued a formal Commitment Letter, and the CDC prepared the preliminary debenture application.
- Phase 2: Due Diligence, Credit Approval & SBA Authorization (Days 16 to 45)
Formal credit approval was granted by both the senior bank’s credit committee and the CDC board. Due diligence reports were commissioned immediately, including an As-Is and As-Complete commercial real estate appraisal, a Phase I Environmental Site Assessment (ESA), and an engineering survey. Upon receipt of satisfactory third-party reports, the complete package was submitted to the SBA Development Company Loan Center. The SBA issued the official SBA Authorization for Debenture Guarantee within 10 business days of submission.
- Phase 3: Construction Escrow Setup, Closing & Initial Disbursement (Days 46 to 75)
Legal counsel drafted construction loan documentation, title insurance commitments, and intercreditor agreements between the senior bank and CDC. A formal pre-construction meeting locked in the fixed-price construction contract with the general contractor. Loan closing occurred on Day 75, at which point equity funds were deposited into an escrow account, and the senior bank disbursed initial funds to start ground-up site work.
Underwriting Document Checklist for Industrial Expansions
Complete documentation accelerates credit review and prevents delays during SBA authorization. Borrowers preparing for an SBA 504 industrial warehouse expansion should assemble the following institutional package:
- Corporate Financial Statements: Three consecutive years of signed federal business tax returns, along with year-to-date balance sheets and profit & loss (P&L) statements dated within 60 days of application submission.
- Personal Financial Documents: Three years of personal tax returns, personal financial statements (SBA Form 413), and resume of management experience for all individual owners holding 20% or greater equity interest.
- Project Budget and Construction Documents: Executed AIA contract or itemized fixed-price construction bid from a licensed general contractor, architectural floor plans, site plans, and complete soft-cost breakdowns.
- Occupancy Certification: Floor plan verification showing that the operating business will occupy at least 51% of the expanded square footage (or 60% for new ground-up construction structures).
- Environmental and Title Documentation: Phase I Environmental Site Assessment (ESA) compliant with SBA Standard Operating Procedures (SOP 50 10), ALTA/NSPS Land Title Survey, and current property deed.
- Debt Schedule: Complete corporate debt schedule detailing all existing institutional notes, vehicle loans, leases, and revolving lines of credit, specifying original balances, current balances, interest rates, monthly payments, and collateral positions.
Structuring Refinance with Expansion under SBA 504 Rules
A powerful feature of the SBA 504 loan framework is the ability to combine facility expansion with debt refinancing under a single transaction. When an owner-occupant decides to expand an existing industrial warehouse or professional services headquarters, any existing commercial mortgage securing the property can often be refinanced directly into the new SBA 504 financing structure, provided specific regulatory criteria are met.
Under the SBA 504 Refinance with Expansion program rules, the existing debt must meet clear eligibility benchmarks:
- Debt Age Requirement: The debt to be refinanced must be at least 6 months old prior to the date of the SBA application.
- Commercial Purpose: At least 85% of the original proceeds of the existing loan must have been utilized for SBA-eligible fixed-asset expenses, such as the initial purchase or construction of the facility.
- Collateral Linkage: The existing debt must be secured by the subject industrial or commercial real estate asset being expanded.
- Payment History: The borrower must demonstrate a clean payment history on the existing debt, showing no delinquencies over 30 days during the preceding 12-month period.
Integrating an existing high-rate or short-term balloon mortgage into an SBA 504 expansion package provides substantial structural relief. For example, if our Midwestern logistics client had carried an existing $1,500,000 debt balance on their original 30,000 square foot facility carrying a 5-year balloon maturity, we could have structured the package to include both the $1,500,000 debt refinance and the $4,500,000 expansion costs into a single $6,000,000 project.
Under expansion refinance rules, the total refinanced debt portion cannot exceed 100% of the net expansion cost portion. Because the expansion cost was $4,500,000, the full $1,500,000 existing mortgage easily qualified for inclusion. By consolidating the existing short-term debt into the 50-40-10 capital stack, the business eliminates upcoming balloon payment threats and establishes one predictable cash outflow.
Key Takeaways: Industrial Expansion Case Study
This industrial warehouse case study highlights how middle-market logistics and commercial operators can leverage the SBA 504 loan structure to drive scalable expansion while maintaining optimal cash reserves:
- Liquidity Preservation: The 10% cash equity requirement ($450,000 on a $4,500,000 budget) preserved over $675,000 in operational working capital compared to standard 25% down conventional bank terms.
- Generational Rate Stability: Securing 40% of the overall capital stack ($1,800,000) through a 25-year fully amortizing, fixed-rate CDC debenture protected the business against intermediate interest rate fluctuations.
- Comprehensive Cost Coverage: Soft costs ($400,000) and specialized heavy equipment fixtures ($300,000) were successfully rolled into the total loan package alongside hard building construction costs ($3,800,000).
- Occupancy Compliance Efficiency: By expanding their operational footprint from 30,000 to 45,000 square feet with 100% owner-occupancy, the borrower satisfied the SBA 51% occupancy requirement for existing facility additions.
- Timely Execution: A structured underwriting protocol enabled intake to closing within a 75-day timeframe, keeping general contractor timelines on schedule.
Frequently Asked Questions About Renovation & Expansion Loans
How can professional services businesses get funding for renovations?
Professional services firms can fund renovations through an SBA 504 loan (for substantial structural additions or owner-occupied building upgrades with 10% equity down), an SBA 7(a) loan up to $5,000,000 for tenant improvements or leased facilities, or a commercial bank line of credit for immediate short-term capital needs.
How should borrowers evaluate the real estate financing company an online loan marketplace on AI agents in CRE?
Borrowers should evaluate an online loan marketplace on speed of intake, automated matching capabilities across commercial lenders, and whether complex underwriting features—such as subordinate liens, multi-draw construction escrow, or SBA 504 refinance guidelines—receive dedicated human advisory support alongside their automated systems.
Can you use an SBA 504 loan to expand an existing warehouse?
Yes. An SBA 504 loan can fund ground-up additions, building retrofits, structural modifications, and physical footprint expansions for owner-occupied industrial warehouses. Eligible project costs encompass site preparation, soft construction fees, architectural engineering, land acquisition, and permanently attached equipment installations.
What is the minimum owner-occupancy requirement for an SBA 504 expansion?
For an existing warehouse or commercial facility being expanded or renovated, the borrowing business must occupy and operate out of at least 51% of the total usable square footage upon project completion. For new ground-up construction additions, initial owner-occupancy must reach 60%, scaling up to 65% to 80% over time.
Can an SBA 504 loan include debt refinance during an industrial expansion?
Yes. Under the SBA 504 Refinance with Expansion program, existing eligible commercial real estate debt on the facility can be folded into the expansion loan package if project criteria are met. The existing debt must be at least six months old and cannot exceed 100% of the expansion costs.