
Direct Answer
To start flipping houses, you generally need between $30,000 and $75,000 in liquid capital when using specialized debt financing on a modest property, or $200,000 to $400,000+ if buying entirely with cash. This money covers a 10% to 20% down payment, closing fees, contractor mobilization outlays before reimbursement draws, financing carry, and a non-negotiable contingency reserve.
Key takeaways
- Liquid requirements depend on financing structure: all-cash deals demand 100% of purchase and rehab capital, whereas leverage requires cash for down payments, closing charges, and upfront repair cycles.
- Construction draw mechanisms require flippers to pay contractors first and seek inspection reimbursements later, demanding active liquidity between milestone payouts.
- The 70% rule serves as an initial pricing rule-of-thumb rather than a substitute for comprehensive cash-flow underwriting.
- Unexpected holding delays, debt service carrying costs, and resale concessions represent the primary budget areas where undercapitalized beginners falter.
- Securing pre-qualification and establishing a liquid buffer before submitting offers is essential to protecting earnest money.
Table of contents
- How much money do you need to start flipping houses? Full capital breakdown
- Worked example: Real-world cash requirements on a $250,000 flip
- What must be true before you make an offer?
- How do you estimate the maximum price without relying on the 70% rule?
- What financing should you arrange before you bid?
- How do you keep the renovation and timeline under control?
- What exit plan should be in place before closing?
- Frequently asked questions
- Next action: Prepare your balance sheet before bidding
How much money do you need to start flipping houses? Full capital breakdown
When asking how much money you need to start flipping houses, many beginners make the fatal assumption that their only hurdle is an earnest money deposit or a lender’s down payment. In our experience underwriting residential transition loans, successful flippers distinguish between their paper purchase budget and their active operational liquidity budget.
Whether you utilize private lending, debt placement, or personal cash, every flip demands liquidity across five mandatory capital buckets:
- Acquisition equity (Down payment): When using short-term financing, lenders typically require first-time borrowers to fund 10% to 25% of the purchase price out-of-pocket, depending on experience and credit history.
- Loan and closing costs: Acquisition fees include origination points (typically 1% to 3%), title insurance, recording fees, appraisals, legal documentation, and transfer taxes. These collectively absorb 2% to 5% of the purchase price.
- Rehab float capital: Construction financing is disbursed in arrears. You must have sufficient cash or custom credit lines for business growth to pay contractors for completed phases before requesting an on-site inspection and draw reimbursement.
- Ongoing debt service and holding carry: You must fund monthly interest payments, property taxes, builder’s risk insurance, utilities (power, water, heating), and HOA dues throughout the construction and marketing cycle.
- Unallocated contingency reserve: A minimum reserve of 10% to 20% of your total renovation budget should remain untouched in your bank account to absorb structural surprises, material cost increases, or extended market listing times.
Worked example: Real-world cash requirements on a $250,000 flip
To see how these capital demands aggregate, examine this representative entry-level investment scenario based on typical 2026 debt parameters:
| Expense Category | Scenario Details | Cash Required Out of Pocket |
|---|---|---|
| Purchase Price & Down Payment | $250,000 purchase price at 85% Loan-to-Cost (15% down payment) | $37,500 |
| Acquisition & Closing Costs | 2 points origination ($4,250), title, appraisal, legal, and transfer fees | $7,500 |
| Renovation Draw Float | Total rehab budget: $50,000; upfront float needed for initial milestones | $10,000 |
| 6-Month Holding Costs | Monthly interest payments, insurance, property taxes, and utility bills | $13,800 |
| Cash Contingency Buffer | 15% reserve against unexpected repairs and permit delays | $7,500 |
| Total Liquid Capital Needed | All out-of-pocket cash required before closing | $76,300 |
In this realistic scenario, even though the lender covers 85% of the purchase and holds a 100% construction escrow, you still require over $76,000 in readily accessible cash to safely execute the transaction from acquisition to resale.
What must be true before you make an offer?
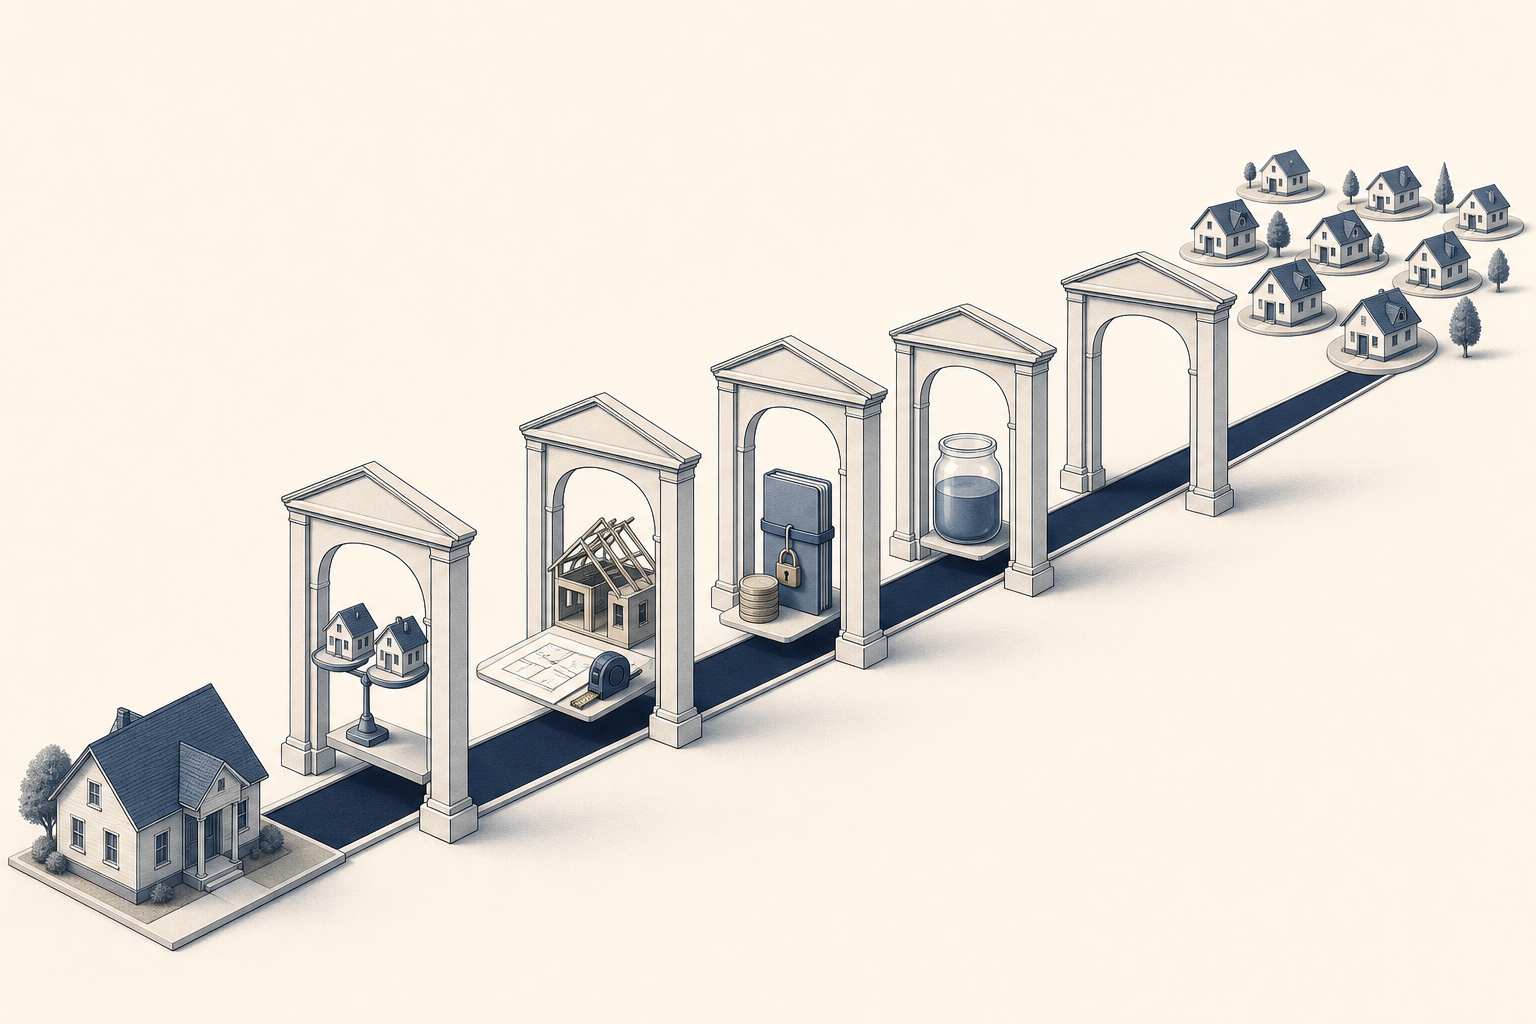
A first flip should clear five rigorous underwriting tests before an offer becomes binding: the resale estimate is mathematically supportable, the scope is thoroughly priced, the funding facility is verified, the project maintains liquidity, and the property addresses a verifiable buyer pool. If any test is unmet, the right move is additional diligence rather than an aggressive bid.
Beginners are frequently seduced by surface indicators: an apparently low list price, a distressed facade, or an up-and-coming ZIP code. We advise investors to start with the deal model instead. A deeply discounted asset can rapidly turn negative if repair estimates fall short, holding periods expand, or renovated comparable sales do not support your anticipated exit price.
Build a standardized pro-forma model for every prospect. It must tabulate expected exit valuation, acquisition cost, closing fees, detailed renovation items, financing points and carry, ongoing utility/tax costs, listing commissions, and a defined minimum margin that compensates for your risk. Assumptions kept invisible are where flip pro-formas fail.
We recommend stress-testing every candidate deal against unfavorable conditions: lower the resale price by 5%, lengthen the execution schedule by 60 days, and inflate construction expenses by 15%. If the projected profit margin evaporates under that modest stress test, pass on the opportunity.
Assemble your core advisory team early: an investor-savvy broker, licensed general contractors, an independent home inspector, an escrow officer, an insurance agent specializing in vacant properties, a CPA, and your lending partner. Each specialist serves to uncover hidden operational costs before purchase funds become non-refundable.
How do you estimate the maximum price without relying on the 70% rule?
The ubiquitous “70% rule” suggests paying no more than 70% of the After-Repair Value (ARV) minus estimated repairs. While helpful as a fast desktop filter, it fails to evaluate local transaction taxes, financing rates, utility carry, and specific margin requirements.
Instead, underwrite backward from verified After-Repair Value (ARV). ARV is the realistic market valuation of the property once planned improvements are finished, established through recent closed sales of renovated, comparable properties within a narrow geographic radius. For historical property valuation insights and transaction trends, reviewing verified housing data from sources like the National Association of Realtors Research helps anchor local projections.
Follow this bottom-up underwriting protocol to determine your Maximum Allowable Offer (MAO):
| Deal Component | How to Calculate It |
|---|---|
| Expected Resale Price (ARV) | Base upon verified closed sales of similar renovated homes within the past 90 to 180 days. |
| Selling & Concession Costs | Deduct 7% to 9% of ARV for listing and buyer broker commissions, transfer fees, staging, and buyer repair concessions. |
| Hard Renovation Costs | Price materials, subcontractor labor, architectural drawings, building permits, and dumpster fees using contractor quotes. |
| Debt & Holding Carry | Compute total loan interest, points, legal fees, builder’s risk insurance, property taxes, and utility bills across the projected schedule. |
| Cash Contingency Reserve | Allocate 10% to 20% of your repair budget for hidden deficiencies behind drywall or beneath foundations. |
| Target Net Profit | Target a fixed dollar amount or minimum percentage return (e.g., 15% of ARV or a minimum of $30,000) reflecting property complexity. |
Subtracting selling costs, renovation expenses, carrying fees, contingency reserves, and target net profit from your ARV yields your absolute ceiling for acquisition basis. Deduct estimated closing costs to arrive at your firm maximum bid.
What financing should you arrange before you bid?
Aligning loan capital to your business strategy is vital. To make confident offers, explore our guide on how to choose the right commercial mortgage for your business goals before engaging sellers.
Key debt mechanisms used in residential flips include:
- Fix-and-Flip Loans: Short-term asset-based loans sized on Loan-to-Cost (LTC) or Loan-to-After-Repair-Value (LTARV). Typically structured as interest-only facilities lasting 6 to 18 months.
- Bridge Debt: Ideal for rapid acquisitions where speed is paramount or where standard lenders decline unpermitted additions. Review multifamily debt placement and bridge loan case studies to understand how transitional capital performs under real execution timelines.
- Private Money or Equity Partners: Individual investors who supply gap equity to meet lender down payment requirements in exchange for an equity share or preferred return.
Review these critical debt parameters with prospective lenders before signing an acquisition contract:
- Exact cash-to-close requirements, verifying whether interest reserves can be financed.
- Interest rates, origination points, underwriting charges, and extension penalty structures.
- Draw reimbursement schedules, required milestone inspections, and holdback release turnarounds.
- Experience tier requirements: whether the lender adjusts leverage based on documented completed projects.
How do you keep the renovation and timeline under control?
Timeline slippage represents an insidious cost center on any flip. Every thirty days of schedule creep adds interest debt service, insurance fees, utility bills, and market risk. Managing renovations effectively requires treating the project as a structured manufacturing operation rather than a DIY hobby.
Establish a line-item Scope of Work (SOW) tied to binding contractor contracts. Segregate tasks into chronological operational phases:
- Demolition and structural stabilization: Foundation repairs, framing adjustments, roof replacements, and trash removal.
- Rough mechanicals and rough inspections: Electrical rough-in, plumbing supply/waste lines, and HVAC ductwork installation.
- Insulation and drywall: Insulation hanging, board installation, taping, and primer coatings.
- Trim, cabinetry, and tile finishes: Interior doors, baseboards, kitchen/bath cabinets, and hard-surface flooring.
- Final mechanicals, punch list, and staging: Fixture sets, painting touch-ups, deep cleaning, and interior staging.
Never advance funds for unperformed work. Pay contractors in milestone draws aligned with your lender’s inspection verification. When unexpected repairs arise, evaluate them strictly: is the repair code-mandated, structural, or value-accretive? If an item does not directly improve appraisal comps or buyer demand, do not authorize a change order.
What exit plan should be in place before closing?
An exit strategy is non-negotiable. While an open-market retail sale to an owner-occupant is standard, your business model must incorporate fallback exits if local sales velocities decelerate.
Pay close attention to seasoning requirements. The Department of Housing and Urban Development enforces stringent anti-flipping rules for Federal Housing Administration (FHA) financing. Per HUD Single Family Housing Policy Handbook 4000.1, resales occurring within 90 days of acquisition are ineligible for FHA-insured mortgages. Properties resold between 91 and 180 days require additional documentation and potentially a second appraisal if the resale price exceeds the acquisition price by 100% or more. If your target market consists heavily of entry-level FHA buyers, your holding timeline must reflect these regulatory guidelines.
When retail sales hit unexpected headwinds, a viable alternative is pivoting into a long-term rental via the BRRRR (Buy, Rehab, Rent, Refinance, Repeat) approach. Long-term repositioning can be capitalized efficiently using DSCR loans for income-producing properties, allowing you to retire expensive short-term bridge debt without relying on personal tax return qualification.
Frequently asked questions
How much money do you need to start flipping houses with no money down?
While marketing seminars promote “no money down” strategies, true zero-capital flips carry substantial operational risk. Real transactions require funds for earnest money deposits, property appraisals, legal closing documents, and emergency contractor payments. Investors who complete deals without their own money typically raise gap funding from private equity partners or structure joint ventures with licensed contractors.
What is the minimum credit score required to finance a flip?
Most asset-based lenders look for a minimum FICO score of 620 to 660 for entry-level fix-and-flip financing, with preferred terms and higher leverage (such as 85% to 90% LTC) reserved for borrowers maintaining scores of 700 or above alongside documented real estate experience.
Do I need to form an LLC before starting my first house flip?
While an LLC is not federally mandated to buy real estate, most commercial and bridge lenders require borrowers to close in a specialized business entity for liability mitigation and commercial exemption standards. Check official U.S. Small Business Administration entity guidance and consult an attorney to determine the optimal legal formation for your target market.
How long does an average house flip take from acquisition to sale?
A typical residential flip takes five to eight months: one month for initial permitting and acquisition, two to three months for active contractor renovation, and two to four months for marketing, buyer contract negotiations, escrow inspections, and loan closing.
Next action: Prepare your balance sheet before bidding
Before submitting offers or placing earnest money at risk, review your balance sheet with clear eyes. Calculate your verifiable liquid reserves, gather proof-of-funds statements, and align with a lending team that understands local construction dynamics.
At Thorne CRE, we assist real estate investors in structuring flexible acquisition financing, bridge debt, and transitional capital tailored to their investment scope. Contact our advisory team today to discuss your target transaction, establish your borrowing capacity, and secure the financing necessary to execute your next project with confidence.