
Mezzanine debt for $30M multifamily acquisitions provides subordinate debt capital that fills the shortfall between senior agency or bank debt (typically 60%–70% LTV) and sponsor equity (10%–15%), bringing total transaction leverage to 80%–90% LTC. On a $30 million multifamily acquisition, a $3M to $6M mezzanine loan preserves liquidity, protects general partner equity from excessive dilution, and finances critical capital expenditure programs without tripping senior debt service covenants.
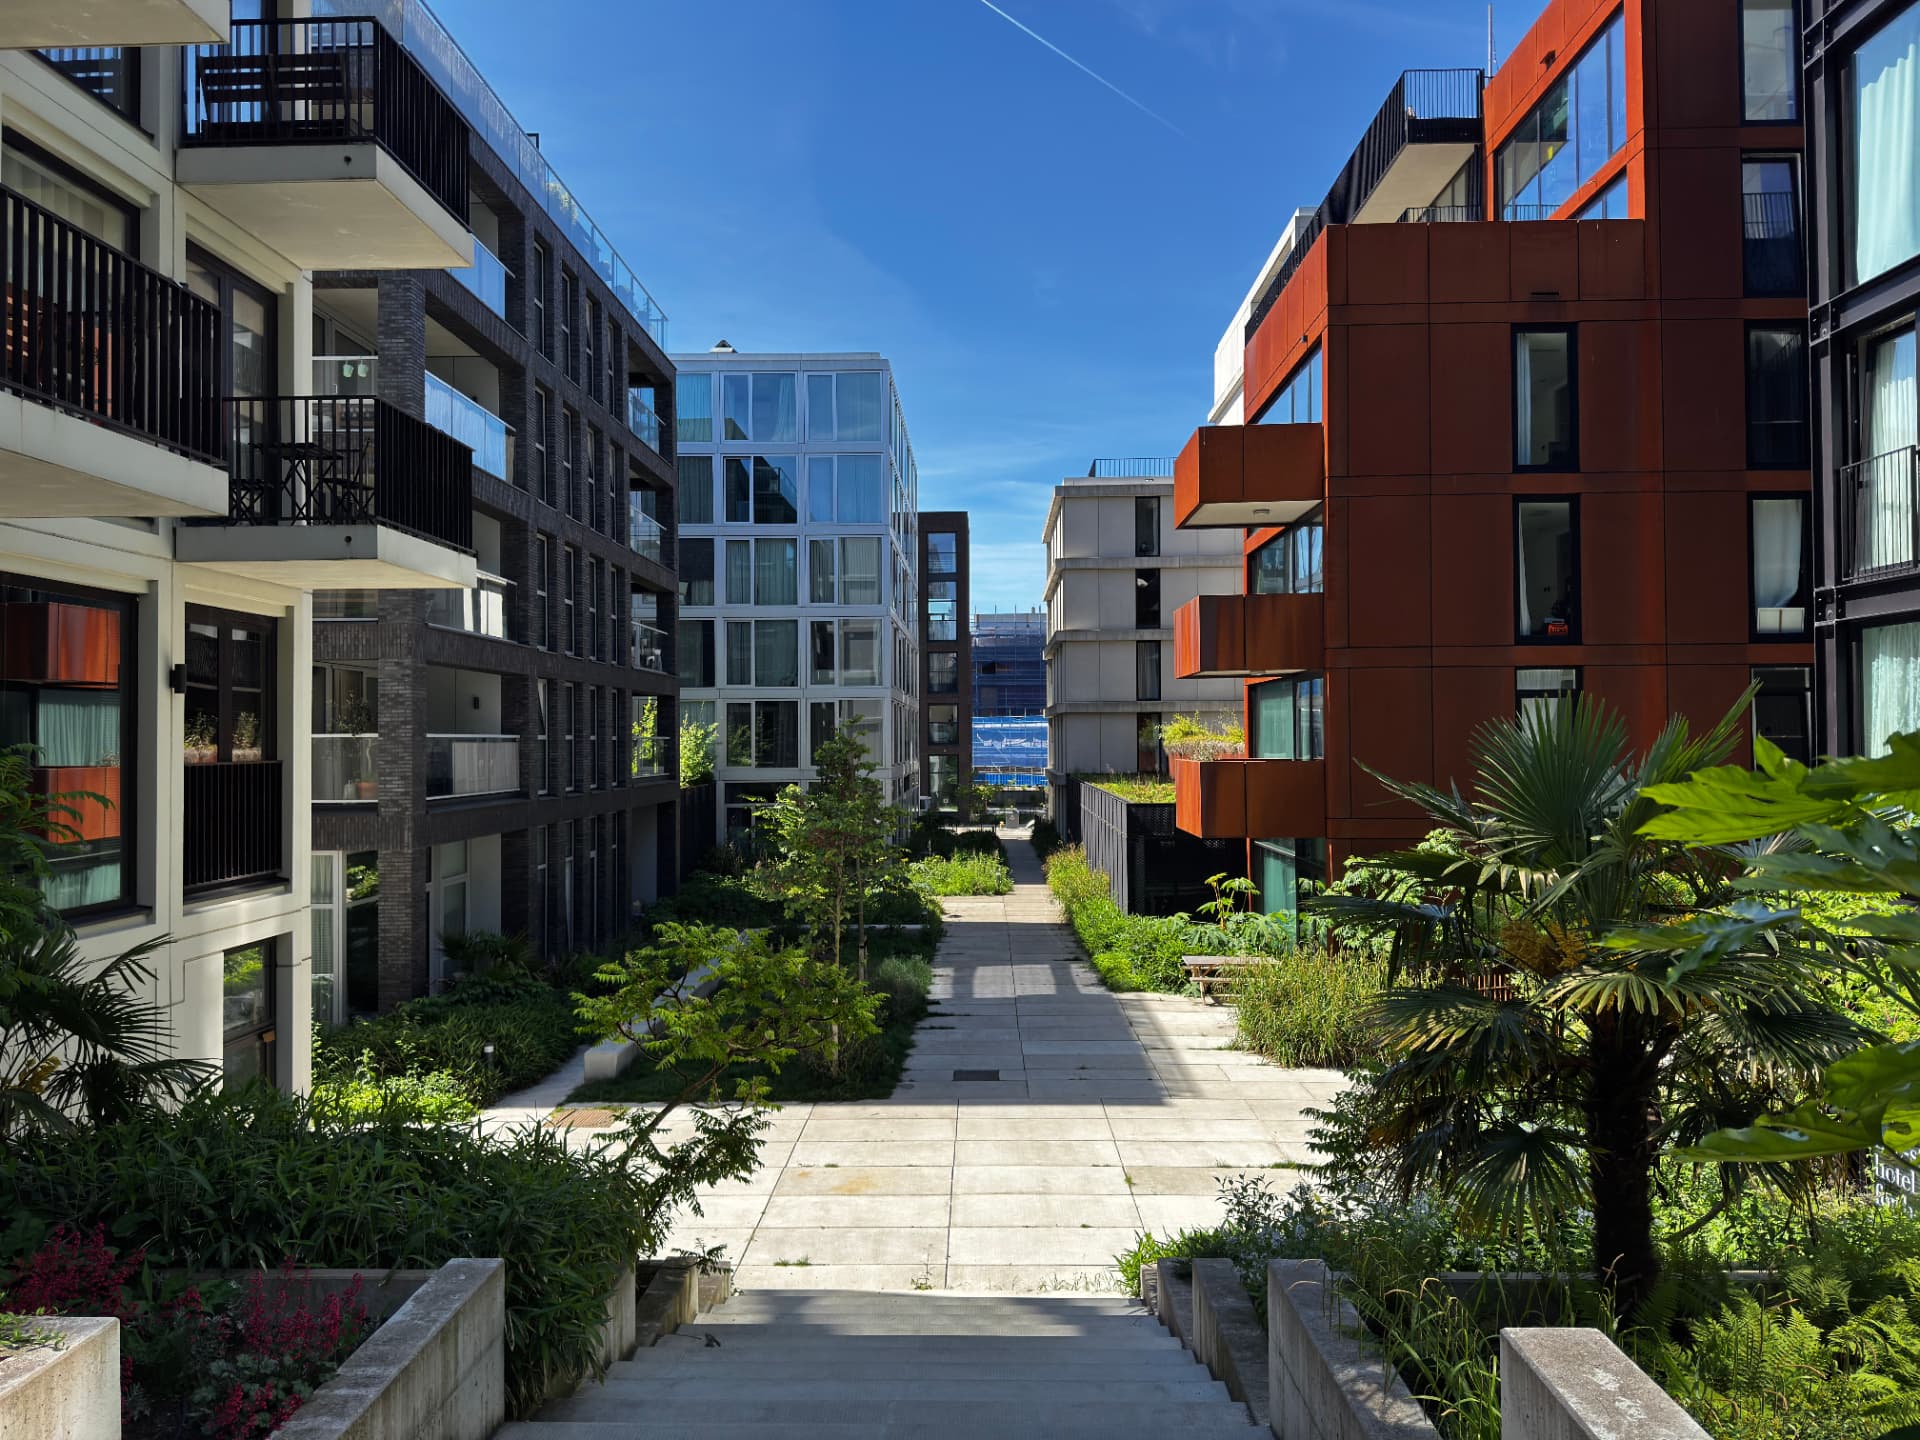
Mezzanine Debt for $30M Multifamily Acquisitions: Direct Overview
In mid-market commercial real estate, securing mezzanine debt for $30M multifamily acquisitions has emerged as an indispensable strategy for acquisition teams, family offices, and private equity syndicates. When buying a 100-to-250-unit garden-style or mid-rise apartment asset valued at $30,000,000, senior institutional lenders rarely stretch beyond conservative debt yield and interest coverage constraints. Mezzanine financing operates directly in that void, slotting in behind the senior mortgage to deliver subordinate liquidity.
Unlike standard junior mortgages, mezzanine financing is strictly collateralized by a pledge of the sponsor’s direct or indirect equity membership interests in the property-owning single-purpose entity (SPE). We structure tailored mezzanine solutions that coordinate cleanly with Fannie Mae, Freddie Mac, balance-sheet banks, and debt funds. If you are assessing capital structures across property categories, review our detailed resource on how to choose the right commercial financing for your property goals.
Current Market Conditions: Why Mezzanine Demand Is Rising for $30M Acquisitions
Transaction activity in the $25M to $40M multifamily sector is accelerating, but the lending environment presents distinct hurdles. Over the past two years, senior commercial lenders have pulled back maximum loan-to-value limits from historical 75%–80% levels down to 60%–68%, largely driven by elevated interest rate floors and stringent debt service coverage covenants. This gap creates significant equity drag on acquisition models.
Several market dynamics explain why demand for mezzanine tranches on $30 million acquisitions is climbing swiftly:
- The Senior Debt Squeeze: Agency and bank underwriters benchmark loans against trailing-12-month net operating income (T12 NOI) using stress-tested interest rates. On a $30M transaction, this cap often limits senior proceeds to between $18M and $20M, requiring the sponsor to assemble over $10M in equity without subordinate leverage.
- Valuation Re-baselining: Multifamily capitalization rates have adjusted, presenting rare opportunities to acquire high-quality Class B and Class A-minus assets at attractive discounts to replacement cost. Sponsors rely on mezzanine tranches to secure these assets before capitalization rates compress again.
- Preserving Internal Rate of Return (IRR): Raising pure LP equity to fund a 40% equity check dilutes general partner promote thresholds. Introducing 15% to 20% mezzanine debt reduces LP equity requirements, enhancing target equity multiples and cash-on-cash metrics.
- Bridge-to-Agency Refinancing: Borrowers often deploy a 24- to 36-month mezzanine tranche to fund value-add renovations, boost rents, and subsequently refinance into permanent agency debt under guidelines established by Fannie Mae Multifamily or Freddie Mac Multifamily.
Eligibility & Underwriting Criteria for $30M Multifamily Mezzanine Debt
Securing mezzanine debt for a $30 million acquisition requires navigating synchronized underwriting between the senior lender and the mezzanine credit committee. We look at both current cash-flow resiliency and the viability of the business plan:
- Combined Leverage (LTC / LTV): Senior loan proceeds plus the mezzanine tranche reach up to 80%–85% loan-to-value (LTV) or up to 85%–90% loan-to-cost (LTC) when a capital improvement budget is factored in.
- Debt Service Coverage Ratio (DSCR): Senior mortgage DSCR must generally clear a minimum of 1.25x to 1.30x on in-place net operating income. Combined (senior plus mezzanine) DSCR typically underwrites at 1.05x to 1.15x based on interest-only payments or stabilized pro-forma operations. For additional underwriting context, explore our guide on expert tips for choosing the right commercial loan.
- Pricing, Yield, and Structure: Full mezzanine yields range from 10.0% to 14.0% per annum, structured as a combination of current-pay coupon (typically 7.0% to 9.5%) and deferred payment-in-kind (PIK) interest (2.0% to 4.5%). Floating tranches are benchmarked over term SOFR published by the Federal Reserve Bank of New York.
- Sponsor Profile & Liquidity: Sponsors typically need a minimum net worth equal to or greater than the full loan amount ($30M combined debt package) and post-closing unencumbered liquid liquidity of at least 10% of the loan amount, alongside a verifiable 3- to 5-year operating track record.
- Capital Expenditure Facility: On value-add multifamily transactions, mezzanine facilities frequently incorporate a delayed-draw feature that funds 100% of unit renovation costs. If substantial redevelopment is involved, review our checklist before applying for construction financing.
Capital Stack Breakdown: $30M Multifamily Acquisition Worked Example
To demonstrate how mezzanine debt transforms sponsor economics, consider a concrete underwriting example of a 180-unit garden community acquired for $30,000,000 with a planned $2,000,000 interior value-add renovation program ($32,000,000 total project cost):
| Capital Layer | Percentage of Stack | Amount ($USD) | Indicative Rate / Yield | Security & Position |
|---|---|---|---|---|
| Senior Debt (1st Lien) | 65.0% LTV | $19,500,000 | SOFR + 2.65% (~7.40%) | First Deed of Trust / Senior Mortgage |
| Mezzanine Debt | 18.75% LTC | $6,000,000 | 11.50% (8.00% Pay / 3.50% PIK) | Pledge of 100% Equity Interests in SPE |
| Sponsor / LP Equity | 20.31% Total Cost | $6,500,000 | Target 18%+ IRR | Subordinated Common Equity |
| Total Capitalization | 100.0% | $32,000,000 | Blended Cost: ~8.85% | Acquisition + $2M Capex |
Without mezzanine financing, the sponsor would need to raise $12,500,000 in equity upfront to complete the acquisition and fund the value-add program. By inserting a $6,000,000 mezzanine debt tranche, the sponsor cuts the required cash equity commitment almost in half—from $12.5M down to $6.5M. This capital efficiency sharply increases project-level equity multiples and frees up capital to pursue concurrent acquisitions.
Intercreditor Dynamics and Equity Foreclosure Mechanics
The foundation of any successful mezzanine financing package on a $30M acquisition is the Intercreditor Agreement (ICA) executed between the senior lender and the mezzanine lender. Because the mezzanine lender does not hold a real estate mortgage, its rights exist through the Uniform Commercial Code (UCC) pledge over equity shares.
Essential components negotiated in the ICA include:
- Notice and Cure Rights: The mezzanine lender receives immediate formal notice of any senior debt default and maintains the unilateral right to cure debt service payments or insurance shortfalls to protect its subordinate position.
- UCC Foreclosure: In an uncured event of default, the mezzanine lender executes a rapid UCC equity foreclosure rather than a multi-year judicial mortgage foreclosure, allowing it to take over ownership and management of the SPE in 30 to 60 days.
- Pre-Approved Qualified Transferees: The senior lender agrees in advance that designated qualified institutional lenders or pre-cleared real estate operating partners can assume ownership through UCC foreclosure without triggering the senior loan’s acceleration clause.
Thorne CRE’s Value Proposition for Multifamily Investors
We work collaboratively with private sponsors, syndicators, and family offices to bridge equity gaps and deliver structured capital with complete certainty of execution. When closing on a $30M apartment asset, sponsors rely on our specialized platform for three distinct advantages:
1. Synchronized Dual-Tranche Structuring
Rather than negotiating with separate senior lenders and subordinate mezzanine funds whose legal teams often clash, we coordinate both layers under one roof or through pre-negotiated co-lender arrangements. This cuts closing times down to 3 to 5 weeks and prevents eleventh-hour intercreditor disputes.
2. Flexible PIK Interest Components
We structure custom mezzanine tranches with payment-in-kind (PIK) provisions that minimize current cash burden during the initial 12 to 24 months of renovations. By capitalizing a portion of the interest accrual until property operations stabilize, we protect project liquidity during turnarounds.
3. Non-Recourse Peace of Mind
All mezzanine facilities for institutional-grade multifamily properties are standard non-recourse, governed strictly by customary carve-out agreements covering bad-boy acts such as fraud, environmental contamination, or unauthorized transfer.
Thorne CRE vs. Traditional Banks: A Side-by-Side Comparison
| Feature | Thorne CRE (Specialized Structured Debt) | Traditional Commercial Banks |
|---|---|---|
| Target Transaction Size | $10M – $50M middle-market multifamily | Typically broad, prioritizing balance-sheet depository clients |
| Maximum Total Leverage | Up to 85%–90% LTC (Senior + Mezzanine) | Strictly capped at 60%–68% LTV |
| Closing Speed | 3 to 5 weeks from term sheet | 60 to 90+ days |
| Payment Flexibility | Customized PIK toggles, extended IO periods | Rigid monthly amortizing schedules |
| Recourse Requirements | Non-recourse with standard carve-outs | Frequently mandates full or partial personal recourse |
| Intercreditor Alignment | Streamlined, established templates with senior debt | Often unaccustomed or resistant to subordinate debt |
Frequently Asked Questions
How does mezzanine debt differ from preferred equity on a $30M acquisition?
While both mezzanine debt and preferred equity sit between senior mortgage debt and common equity, mezzanine debt is a loan governed by a credit agreement and secured by a UCC pledge of membership interests. In contrast, preferred equity represents an equity investment governed by the company’s operating agreement. Mezzanine debt gives lenders debt-style remedies (UCC foreclosure), whereas preferred equity holders typically exercise change-of-control voting rights.
What is the minimum debt service coverage ratio (DSCR) required?
Senior lenders usually require an in-place DSCR of 1.25x to 1.30x on senior mortgage debt. When mezzanine debt is added, underwriters look for a combined DSCR (covering senior plus mezzanine current debt service) of at least 1.05x to 1.15x, often evaluated on 12-month trailing cash flow or near-term stabilized projections.
What are current interest rates and terms for $30M acquisition mezzanine loans?
Total mezzanine return yields currently range from 10.0% to 14.0% per annum. Terms typically match the senior bridge or agency loan (typically 2 to 5 years), with interest structured as 7%–9% current cash-pay interest plus 2.5%–4.0% deferred payment-in-kind (PIK) interest, tied to prevailing SOFR benchmarks.
Can mezzanine debt be used for capital expenditure and unit renovations?
Yes. Many mezzanine facilities for $30M acquisitions are structured with a delayed-draw future funding facility to cover 100% of budgeted unit interior renovations, common area upgrades, and exterior improvements, ensuring sponsors do not have to hold surplus equity reserves from day one.
Next Steps: Partnering with Thorne CRE on Your Next Acquisition
Executing a successful $30M multifamily acquisition requires structured debt that optimizes your leverage while protecting operational execution. Our team provides responsive underwriting, deep agency familiarity, and flexible subordinate capital tailored to your acquisition timeline.
To evaluate your capital stack or receive a preliminary terms sheet within 48 hours, contact the Thorne CRE structured finance desk today. Send your trailing-12 financials, pro-forma model, and purchase contract summary to our underwriting team to get started.