
We structure SBA 504 multi-tenant financing where third-party senior lenders incur a one-time 0.50% participation fee. Additional fees include CDC debenture costs of 2.15% to 2.65%, closing legal fees, and standard bank underwriting charges.
Key Takeaways
- Third-Party Lender (TPL) Participation Fee: Senior bank lenders incur a one-time 0.50% (50 bps) fee on their first mortgage portion, which is customarily passed through to the borrower at closing.
- CDC Debenture Program Fees: Upfront CDC/SBA fees total between 2.15% and 2.65% of the 40% debenture amount, all of which can be financed directly into the loan.
- Multi-Tenant Occupancy Rules: The borrower must occupy at least 51% of existing rentable square footage (60% for new construction), while the remaining 49% can generate rental income.
- Technical & Closing Costs: Account for out-of-pocket costs including MAI appraisals, Phase I environmental reports, property condition assessments, title insurance, and legal fees.
The SBA 504 Capital Stack & Third-Party Lender Participation
The Small Business Administration (SBA) 504 loan program provides long-term, fixed-rate financing for major fixed assets, primarily owner-occupied commercial real estate. When financing commercial property through this program, we utilize a tiered capital structure that distributes credit risk across three distinct participants: a senior third-party lender, a Certified Development Company (CDC) acting on behalf of the SBA, and the borrowing entity. To learn more about how structure affects eligibility, explore our guide on SBA 504 capital stack structures.
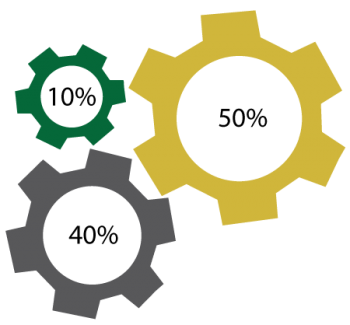
In a standard transaction, the capital stack is allocated as follows:
- 50% Senior Third-Party Lender Loan: A conventional bank, credit union, or non-bank lender originates a first mortgage covering at least 50% of the total project cost. This lender holds the primary lien position on the underlying real estate asset.
- 40% CDC/SBA Debenture: A licensed CDC originates a junior mortgage covering up to 40% of the project cost. This note is 100% backed by an SBA-guaranteed debenture sold directly to private institutional investors.
- 10% Borrower Equity Injection: The borrowing small business injects a minimum of 10% equity toward the total project costs for standard multi-tenant or single-tenant real estate acquisitions.
For commercial real estate assets designated as special-use properties, or for operating companies with less than two years of management history, equity injection requirements increase. To evaluate down payments across property types and special-use classifications, read our comprehensive analysis of SBA 504 down payment requirements for multi-tenant CRE for detailed equity tiering.
Multi-tenant commercial real estate qualifies under SBA 504 program guidelines provided the operating company physically occupies a minimum of 51% of the property’s total rentable square footage (RSF) for existing acquisitions. For ground-up new construction projects, the business must immediately occupy 60% of the RSF, with a formal plan to occupy up to 80% within ten years. The remaining 49% (or 40% for ground-up developments) may be leased to third-party commercial tenants. This income-producing space provides cash flow that supplements primary business operations and aids in debt service coverage ratio (DSCR) qualification.
Understanding the Third-Party Lender Participation Fee (0.50%)
Under federal regulations governing the SBA 504 program—specifically codified in 13 CFR § 120.972—the SBA assesses a statutory fee on the senior third-party lender participating in the transaction. This charge is formally designated as the Third-Party Lender (TPL) Participation Fee.
The TPL participation fee is a one-time charge equal to 0.50% (50 basis points) calculated directly against the principal amount of the third-party lender’s senior loan. It is not calculated against the total purchase price of the real estate, nor is it based on the CDC debenture amount.
The statutory basis for this fee rests on the structural credit enhancement the SBA provides to the commercial bank. By placing the CDC debenture in a subordinate second-lien position behind the senior lender’s first mortgage, the SBA absorbs significant default risk. The senior bank achieves a comfortable 50% loan-to-value (LTV) ratio on commercial real estate collateral. In exchange for receiving a lower-risk senior lien position supported by federal intervention, the SBA levies the 0.50% participation fee on the third-party institution.
While the regulation charges this fee directly to the senior bank, federal rules explicitly permit the bank to pass this expense directly through to the borrower at loan closing. In practice, senior lenders include this 50 basis point fee on the settlement statement (HUD-1 or ALTA Combined Settlement Statement) as a standard line-item closing cost paid out of borrower funds.
Calculating the 0.50% Senior Lien Fee
To demonstrate how the TPL participation fee applies within a standard commercial acquisition, consider a multi-tenant office building acquired for a total project cost of $5,000,000. Assuming standard 50-40-10 capital allocation, the underwriting breakdown proceeds as follows:
| Capital Stack Component | Percentage Share | Dollar Amount | Associated TPL Fee (0.50%) |
|---|---|---|---|
| Senior Bank First Mortgage | 50% | $2,500,000 | $12,500 |
| CDC / SBA Second Debenture | 40% | $2,000,000 | N/A (SBA Fee Stack Applies) |
| Borrower Equity Injection | 10% | $500,000 | N/A |
| Total Project Cost | 100% | $5,000,000 | $12,500 Total TPL Fee |
In this scenario, the senior lender originates a $2,500,000 first mortgage. The 0.50% participation fee assessed on that loan amount equals exactly $12,500. This charge is remitted by the closing attorney or title company directly to the SBA’s Central Servicing Agent (CSA) upon loan closing, with the ultimate expense absorbed by the borrower as a closing cost.
As senior loan volume increases, the absolute cash requirement for the TPL fee scales proportionally. On large-format commercial deals, this expense represents a substantial cash outlay at the closing table that we build into initial liquidity and closing capital calculations.
Who Pays the Third-Party Lender Fee?
Contractual responsibility for the TPL fee exists on two levels: legal assessment versus practical execution.
Legally, the SBA bills the third-party lender. The contractual relationship for the fee exists between the SBA, the designated CDC, and the senior bank. The SBA requires the senior lender to execute a Third-Party Lender Agreement (SBA Form 2287) prior to debenture closing. Under this agreement, the bank confirms its first lien status, agrees to subordinate the second mortgage to the CDC, and accepts liability for paying the 0.50% participation fee.
Practically, commercial loan commitment letters issued by senior lenders contain fee-pass-through clauses. These contractual terms stipulate that all regulatory, legal, program, and third-party fees incurred by the bank to structure and close the SBA 504 loan are the sole responsibility of the borrower. Consequently, while the bank legally remits the funds to the SBA, the borrower finances or pays the fee out of pocket at settlement.
Complete CDC Debenture & SBA Fee Breakdown
Beyond the senior lender’s 0.50% TPL participation fee, the CDC debenture portion of the transaction incurs a distinct set of upfront program fees. These fees typically total between 2.15% and 2.65% of the debenture amount (the 40% second mortgage piece), depending on debenture maturity and market conditions. You can read more about debenture costs in our guide to CDC debenture fees and pricing.
Unlike third-party bank fees, the SBA allows borrowers to roll these upfront debenture fees directly into the 504 loan principal. As a result, these costs do not require additional out-of-pocket cash from the business owner at settlement; instead, the gross debenture amount is adjusted upward to cover the net eligible project costs plus program fees.
| Fee Breakdown Item | Fee Percentage / Rate | Calculation Basis | Financed into Loan? |
|---|---|---|---|
| CDC Processing Fee | 1.50% | Net Debenture Principal | Yes |
| SBA Guarantee Fee | 0.50% | Net Debenture Principal | Yes |
| Debenture Underwriters’ Fee | 0.40% (25-Yr) / 0.35% (10-Yr) | Gross Debenture Principal | Yes |
| Funding Fee (CSA Fee) | 0.25% | Net Debenture Principal | Yes |
| CDC Legal Closing Fee | $2,000 – $3,000 (Flat Fee) | Per Transaction Standard | Yes |
| Senior TPL Participation Fee | 0.50% | Senior Bank First Mortgage | Paid at Closing |
Each fee component within the CDC debenture serves a specific administrative function across the execution lifecycle:
- CDC Processing Fee (1.50%): Covers the CDC’s expenses for underwriting, packaging, processing, and submitting the loan application to the SBA’s Development Company Loan Center. This fee is earned upon issuance of the SBA Authorization.
- SBA Guarantee Fee (0.50%): A one-time fee paid directly to the SBA to offset federal credit risk for backing the debenture.
- Underwriters’ Fee (0.40% or 0.35%): Paid to the investment banking syndicate that markets and sells the 504 debentures to private institutional pool buyers. For standard 25-year real estate debentures, this fee is set at 40 basis points (0.40%). For 10-year debentures (typically equipment transactions), it drops to 35 basis points (0.35%).
- Funding Fee (0.25%): Paid to the Central Servicing Agent (Wells Fargo Corporate Trust Services) for managing debenture issuance, distribution of proceeds, and ongoing debt collection over the loan life.
Closing Legal Fees and Administrative Expenses
In addition to percentage-based program fees, SBA 504 transactions require fixed administrative and closing costs that must be accounted for during underwriting.
The CDC retains specialized legal counsel to draft debenture loan documentation, review title commitments, verify municipal compliance, and record second mortgages. The SBA caps the standard CDC closing legal fee—typically between $2,000 and $3,000 for standard real estate transactions. Complex multi-tenant transactions involving intricate title issues or municipal leasehold structures may incur higher legal costs subject to SBA approval.
Beyond legal closing fees, borrowers must budget for standard third-party technical reports required by both the senior lender and the CDC:
- MAI Commercial Appraisal: Must be ordered directly by the senior lender and compliant with Uniform Standards of Professional Appraisal Practice (USPAP) and SBA SOP 50 10 7 standards. Costs range from $4,000 to $8,000 depending on property scale and tenant mix complexity. Review our commercial real estate appraisal guide for details on multi-tenant valuations.
- Phase I Environmental Site Assessment (ESA): Required for all commercial acquisition properties. If historical use suggests potential contamination (e.g., dry cleaners, auto repair, industrial tenancy), a Phase II ESA testing program may be required. Phase I reports range from $2,500 to $4,500.
- Property Condition Assessment (PCA): Often required by senior bank underwriters on multi-tenant commercial assets to evaluate mechanical, electrical, plumbing, structural, and roofing reserves over a 10-year holding period. PCA costs range between $2,000 and $5,000.
- ALTA Title Insurance & Land Survey: Lenders require both senior first-position and CDC second-position title policies, alongside an updated ALTA/NSPS land title survey detailing easements, lease boundary lines, and structural encroachments.
Multi-Tenant Specific Costs and Fee Optimization Strategies
Underwriting multi-tenant commercial real estate under the SBA 504 framework adds operational considerations that do not exist in single-tenant transactions. Because third-party tenants generate income supporting the property, we must carefully review lease terms, tenant improvement obligations, and subordination agreements to avoid execution delays and unnecessary capital strain.
Managing Tenant Improvement (TI) Reserves
When purchasing a multi-tenant property with vacant space or space needing renovation, borrowers often build Tenant Improvement (TI) allowances and capital expenditures into the total project cost. The SBA allows business owners to finance build-outs for both the space they will occupy and third-party tenant spaces, provided total occupancy thresholds are maintained.
However, allocating TI funds across multi-tenant footprints alters fee structures and escrow mechanics:
- If TI allocations are financed through the SBA 504 loan, funds are held in a specialized CDC escrow account post-closing. The CDC charges administrative disbursement fees to inspect completed work and release funds to contractors.
- If tenant improvements are executed prior to loan closing, work must be verified via mechanics lien waivers and professional architectural sign-offs to ensure clear title status for both the senior bank and the SBA second lien.
Lease Review Legal Fees and Subordination Agreements
Multi-tenant commercial properties require thorough legal analysis of existing leases. The senior lender and CDC legal teams must ensure that third-party tenant leases do not contain clauses that impair the mortgage holders’ security interests.
Key legal requirements for multi-tenant property leasing include:
- Subordination, Non-Disturbance, and Attornment Agreements (SNDAs): Third-party tenants occupying significant square footage must execute SNDAs. This legal instrument subordinates the tenant’s leasehold interest to the senior bank’s mortgage while guaranteeing the tenant can remain in the space if a default occurs, provided the tenant complies with lease terms. Drafting and negotiating customized SNDAs with corporate tenants increases closing legal fees.
- Tenant Estoppel Certificates: Senior lenders require executed estoppel certificates from all existing commercial tenants prior to funding. Estoppels confirm current rent terms, security deposit holdings, lease expiration dates, and verify that the seller/landlord is not in default under existing lease agreements.
- Master Lease Structures: If the operating company leases property through an affiliated real estate holding company (an Eligible Passive Company, or EPC), a formal master lease between the EPC and the Operating Company (OC) must be drafted. The SBA requires the rent paid by the OC to the EPC to equal debt service payments on the first and second mortgages plus necessary property taxes, insurance, and maintenance expenses.
Structuring Interim Construction or Bridge Financing Fees
A critical operational mechanic of the SBA 504 program is that the CDC debenture does not fund on the day of property purchase. SBA debentures are pooled and sold on Wall Street once per month. Consequently, a temporal gap exists between real estate closing and the actual sale of the debenture. Learn more about managing funding timing in our overview of interim bridge financing for 504 loans.
To bridge this gap, the senior third-party lender (or a designated interim lender) provides temporary financing covering the CDC’s 40% debenture piece alongside its own 50% first mortgage. This structure means the senior bank finances 90% of the total project cost at purchase closing.
Once the debenture pool sells—typically 30 to 90 days post-closing—the proceeds of the debenture sale pay off the bank’s temporary 40% bridge loan, stepping the bank’s exposure back down to its permanent 50% first lien position.
This structural requirement creates additional transaction fees that must be budgeted during underwriting:
- Interim Loan Origination Fees: Senior banks often charge a modest origination or administrative processing fee (typically 0.50% to 1.00%) on the 40% interim bridge loan component for holding the extra credit risk prior to debenture takeout.
- Interim Interest Costs: The borrower pays interest-only payments on the 40% interim loan from the day of property closing until the date the debenture fully funds. If benchmark rates rise during this window, interim debt service costs increase accordingly.
To optimize these expenses, we coordinate debenture submission schedules to align closing dates with upcoming SBA funding cycles, minimizing the duration of interim bridge financing and reducing total net interest expenses for the borrower.
How to Calculate and Navigate SBA 504 Multi-Tenant Fees
- Establish Total Project Costs & Capital Allocation: Aggregate the total purchase price, renovation costs, tenant improvement reserves, and eligible soft costs. Divide the total into the 50-40-10 capital stack (50% senior bank loan, 40% CDC debenture, 10% borrower equity injection).
- Calculate the 0.50% TPL Participation Fee: Multiply the senior bank’s 50% loan amount by 0.50% (0.0050) to determine the exact third-party lender participation fee due at settlement.
- Estimate CDC & SBA Debenture Program Fees: Calculate 2.15% to 2.65% of the 40% debenture portion to determine total program fees (CDC processing, SBA guarantee, underwriting, CSA funding, and legal fees). Add these to the gross debenture principal so they can be financed into the loan.
- Account for Technical Reports & Legal Expenses: Budget for out-of-pocket technical expenses including the MAI appraisal ($4,000–$8,000), Phase I ESA ($2,500–$4,500), PCA ($2,000–$5,000), title insurance, and SNDA lease review fees.
- Plan for Interim Interest & Settlement Closing Costs: Estimate 30–90 days of interim bridge interest on the 40% debenture portion prior to debenture sale, and include all non-financeable closing costs in your final cash-to-close calculations.
Frequently Asked Questions
What is the third party lender participation fee on an SBA 504 loan?
The third-party lender participation fee is a one-time fee equal to 0.50% (50 basis points) charged on the senior bank lender’s portion of the SBA 504 loan structure. Codified under 13 CFR § 120.972, it compensates the SBA for providing a second-lien position that reduces senior bank risk to a 50% LTV.
Who pays the SBA 504 third party lender participation fee?
Although assessed by the SBA directly to the senior third-party lender for participating in the 504 program, lenders customarily pass this fee through to the borrower at closing. It is included as an explicit line-item closing cost on the settlement statement and paid out of borrower funds.
What are the CDC and SBA fees for a 504 commercial real estate loan?
CDC and SBA debenture fees total between 2.15% and 2.65% of the SBA debenture amount. This includes a 1.50% CDC processing fee, a 0.50% SBA guarantee fee, debenture underwriting fees (0.35%–0.40%), a 0.25% funding fee, and a standard CDC legal fee of $2,000 to $3,000. These costs can be financed directly.
How does a multi-tenant property structure work under SBA 504 rules?
Under SBA 504 rules, the borrowing small business must occupy at least 51% of an existing multi-tenant commercial property’s rentable square footage, while the remaining 49% can be leased to third-party tenants to generate rental income. For ground-up construction, initial owner occupancy must be at least 60%.
References
Sources reviewed while researching sba 504 loan third party lender multi tenant fee structure, taken from the US search results on 2026-09-20.
- 504 loans – Small Business Administration – SBA — sba.gov
# 504 loans
## Search SBA.gov
Search SBA.govSearch
×
- SBA 504 Down Payment Requirements for Multi-Tenant CRE — thornecre.com
SBA 504 loans require a 10% down payment for multi-tenant properties with 51% owner occupancy. Learn equity injection tiers, occupancy rules, and terms. - SBA 504 Q&A: Third Party Lender Participation Fee — ffcfc.com
The third party lender fee is a one-time participation fee equal to .50 basis points on the lender’s participation in the project. - How SBA 504 Tenant Improvements Work: A Guide for Lenders — cdcloans.com
This program typically requires only 10 percent down, with 40 percent funded by an interim lender and 50 percent by a conventional lender, … - SBA 504 Basics – Southeast Texas Economic Development Foundation — setedf.org
The third-party lender (bank or credit union) will finance 50% of the project; Third Party Lender $1,000,000. Total Project Cost $2,000,000 - 504 Loan Calculator | Evergreen Business Capital — evergreen504.com
# 504 Loan Calculator*
## Use this simple tool to explore SBA 504 financing options. Refer to the rest of our website to learn more about the SBA 504 program, eligibility, and the SBA 504 loan structure.
### Estimated Debt Service
SBA fees 6The SBA fees are 2.65% of the SBA 504 loan plus legal fees of $2000 for SBA l
- The 504 Loan Program – SCTD Loans — sctdloans.org
# The 504 Loan Program
## [](https://sctdloans.org/wp-content/uploads/2015/02/Percent-Cogs.png) Program Details
The fee structure is prohibitive for smaller transactions, but they may be considered in certain circumstances. - [PDF] SBA’s Certified Development Company/504 Loan Program — occ.gov
# I. What Is the SBA 504 Loan Program?
## Financing Structure
A 504 project is financed by three parties: (1) a bank loan, secured with a first lien, typically covering 50 percent of the project’s cost; (2) a CDC loan secured with a second lien and backed by a 100 percent SBA-guaranteed debenture15covering a maximum of - SBA 504 Q&A: The Third Party Lender and the 504 Closing Process — ffcfc.com
The Third Party Lender is subject to a one-time participation fee of 0.50% of the senior mortgage loan. This fee may be paid by the Third Party Lender or …
SERP features this page targets
| Feature | Likelihood | How this page wins it |
|---|---|---|
| Featured Snippet (Paragraph) | 85% | Key Takeaways Summary Section |
| People Also Ask | 90% | H2 Question Blocks and FAQ Accordion |
| Fee Breakdown Table | 75% | HTML Comparison Table Block |
| AI Overview | 80% | Structured Comprehensive Fee List |