
Construction projects rarely stick strictly to the original blueprint. When unexpected scope shifts, site complications, supply chain bottlenecks, or cost overruns emerge, your financial strategy needs to respond immediately. Adaptive construction financing is a flexible commercial real estate funding structure designed to accommodate mid-project scope changes, budget overruns, and timeline adjustments through flexible draw schedules, expandable loan sizing, and customized interest reserves. At Thorne CRE, we specialize in mid-project restructuring, tailored debt facilities, and cost overrun solutions to ensure your commercial builds stay on schedule and within budget.
Whether you are managing a major commercial build or navigating the complex capital stacks outlined in our ground-up construction development financing pillar guide, unexpected variables are an operational reality. Conventional construction loans often impose rigid covenants and disbursement schedules that can freeze funding precisely when speed is most vital. By transitioning to an adaptive capital strategy, developers and commercial sponsors protect their equity, satisfy general contractors, and sustain on-site momentum.
Adaptive Financing Solutions for Commercial Construction
When commercial construction plans pivot, relying on an unyielding capital stack introduces severe friction. Traditional lending guidelines mandate rigorous pre-approvals for every minor budget reallocation, creating administrative delays that ripple through subcontractors and trade schedules. Adaptive financing structures, conversely, function as a stabilizing foundation when physical builds encounter real-world complexity.
Handling Scope Shifts with Ease
When project scope expands due to municipal zoning updates, tenant-requested interior buildouts, or unforeseen civil engineering requirements, rapid access to capital prevents costly job-site shutdowns. Adaptive construction loans provide fluid capital deployment, enabling developers to modify funding allocations dynamically without halting work. To see how dynamic capital preserves project value across distinct stages, review how construction loans drive project success and growth.
Without flexible draw schedules, a sudden scope expansion forces developers to drain operational liquidity or settle disputes with delayed subcontractors. Adaptive debt facilities allow lenders and borrowers to recalculate disbursements and draw benchmarks, ensuring materials are ordered on time and milestones remain achievable.
Managing Delays and Unexpected Cost Overruns
Weather disruptions, supply chain bottlenecks, and specialized labor shortages frequently stretch commercial construction schedules beyond initial projections. Extended timelines directly increase carry costs, architectural inspection billings, and debt service obligations. Industry research from the Urban Land Institute highlights proactive risk management and adaptive contingency reserves as critical factors separating resilient commercial projects from distressed developments.
Incorporating dedicated cost overrun funding and flexible interest reserve facilities directly into your debt terms ensures that unanticipated line-item increases do not freeze job-site activities. When interest reserves can be extended or rebalanced alongside revised construction milestones, debt service payments continue smoothly even if substantial completion moves outward by several months.
Thorne CRE: Your Commercial Financing Partner
Partnering with dedicated commercial debt advisors transforms financing uncertainty into strategic execution. At Thorne CRE, we structure solutions tailored to mid-market developers, multi-phase renovations, and ground-up builds. Discover how customized debt structures sustain momentum from the earliest planning stages in our breakdown of tailored construction loans powering project success.
Flexible Commercial Capital Structures
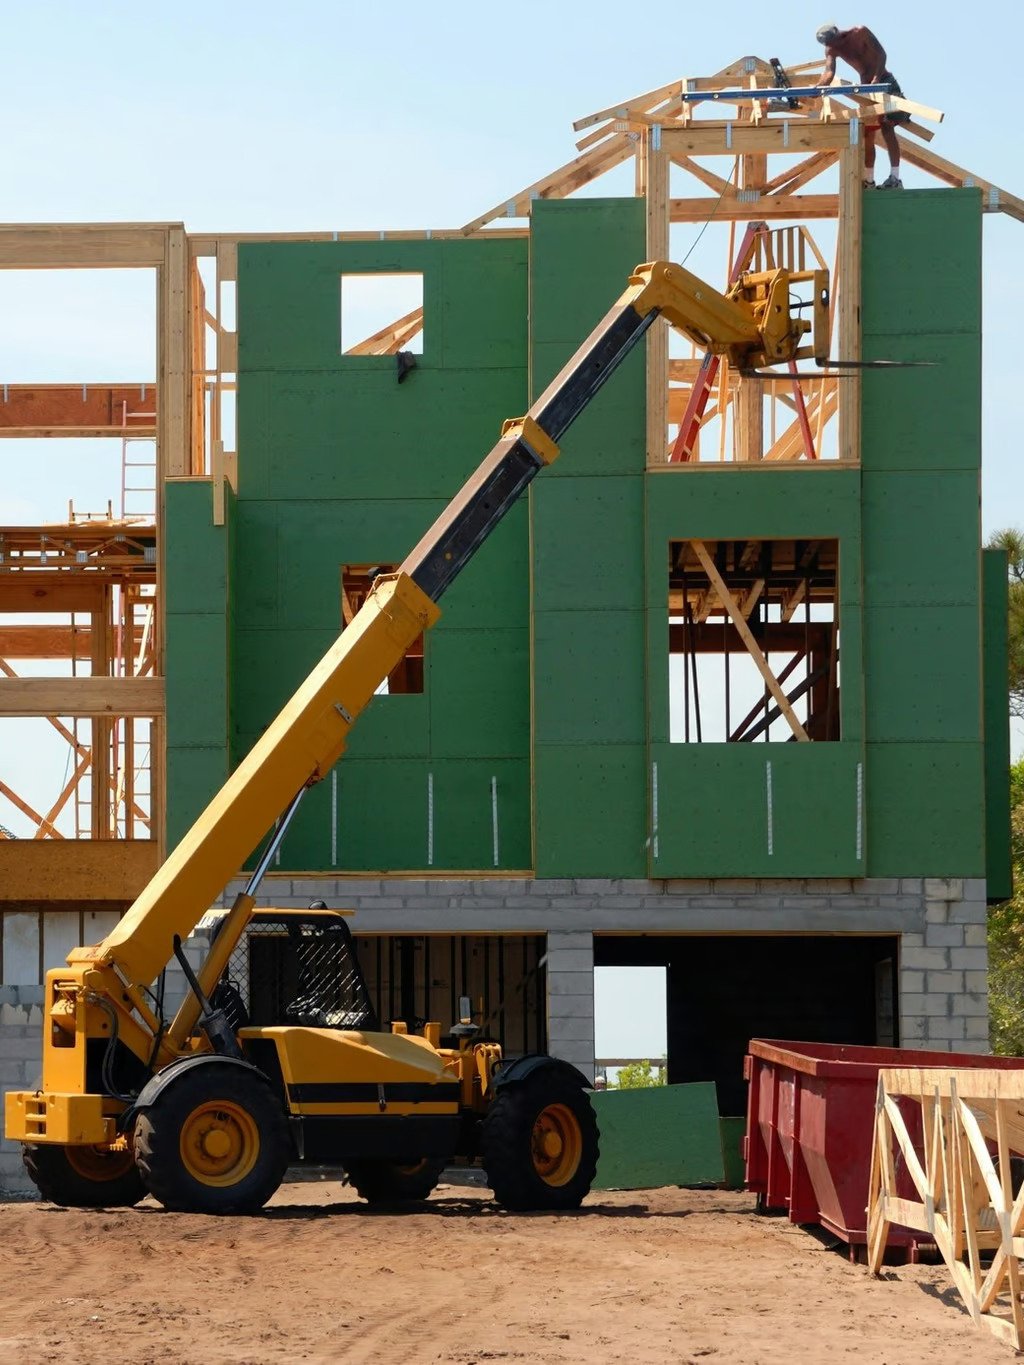
Every commercial development carries distinct site characteristics, physical risk profiles, and capital requirements. Selecting an adaptable financing mechanism guarantees liquidity across every phase of site work, framing, and final tenant occupancy.
Tailored Capital for Evolving Needs
Tailored commercial loans function as dynamic tools rather than rigid liabilities. By matching financing milestones directly to cash flow requirements and verifiable construction progress, project sponsors retain operational agility under changing market conditions. For owner-occupied properties transitioning from construction to permanent financing, evaluating long-term SBA structures is often beneficial; explore our comprehensive comparison of SBA 504 vs 7a loans for owner-occupied real estate.
Bridge, Mezzanine, and Mid-Project Refinancing Options
When unexpected capital deficits occur mid-build, several targeted debt instruments can bridge the funding gap without compromising borrower control:
- Commercial Bridge Loans: Deliver short-term liquidity to maintain progress between development phases, refinance maturing senior notes, or fund sudden architectural redesigns.
- Mezzanine Debt & Preferred Equity: Infuses subordinate capital into the stack, bridging the gap between existing senior debt and sponsor equity without forcing dilutive partnership reorganizations.
- Mid-Project Refinance: Restructures or expands primary debt mid-construction to incorporate revised budgets, lower carry burdens, or adjust completion schedules. For real-world applications of mid-stream restructurings, read our flexible construction funding and SBA takeout case studies.
Navigating Change Orders and Site Contingencies
Subsurface soil abnormalities, concealed structural conditions during adaptive reuse, and municipal code adjustments inevitably prompt contractor change orders. Dedicated change order financing creates an approved contingency mechanism within the primary loan or via a supplemental facility. This enables owners to verify, approve, and disburse payments swiftly, keeping trade crews productive and materials arriving on schedule.
Worked Scenario: Scope Expansion & Cost Overrun Analysis
To understand how adaptive financing functions in practice, consider the following explicitly hypothetical planning scenario for a mid-market commercial light-industrial development. This model illustrates the financial impact of scope shifts and how flexible debt mechanisms mitigate cash shortfalls.
| Metric | Original Budget | Revised Scope & Overrun | Net Capital Adjustment |
|---|---|---|---|
| Total Hard & Soft Costs | $8,000,000 | $9,200,000 | +$1,200,000 (15% Increase) |
| Senior Construction Facility (70% LTC) | $5,600,000 | $6,440,000 | +$840,000 Adaptive Facility Upsize |
| Sponsor Equity & Contingency Reserve | $2,400,000 | $2,760,000 | +$360,000 (30% Co-Investment) |
| Construction Timeline | 12 Months | 16 Months | +4 Months Extended Horizon |
| Hypothetical Interest Reserve | $380,000 | $520,000 | +$140,000 Capitalized Reserve |
In this hypothetical calculation, the commercial project encounters unexpected civil utility upgrades and tenant improvements, driving total costs from $8,000,000 to $9,200,000—a net cost overrun of $1,200,000, representing a 15% budget increase. Concurrently, the build horizon extends from an illustrative planning timeframe of 12 months to an adjusted illustrative timeframe of 16 months.
Under a rigid loan agreement, the sponsor would face an immediate out-of-pocket cash call of $1,200,000 plus additional debt service payments for the extended 4-month build. With adaptive construction financing:
- The senior facility is upsized from $5,600,000 to $6,440,000, maintaining the agreed 70% loan-to-cost (LTC) ratio and absorbing $840,000 of the expansion.
- The sponsor injects $360,000 to satisfy their 30% pro-rata equity requirement, rather than exhausting liquid operating reserves.
- The lender capitalizes an additional $140,000 into the project’s interest reserve, covering the extended carrying costs across the additional 4-month construction window without triggering technical payment defaults.
Checklist: Preparing for Adaptive Financing Restructuring
When project parameters deviate from the initial loan submission, commercial developers must present organized documentation to secure swift lender approvals. Federal lending frameworks, such as the FDIC Guidelines on Commercial Real Estate Lending, require financial institutions to follow prudent underwriting and risk-monitoring standards while assessing modified construction draw plans. Maintaining the following checklist ensures efficient underwriting review:
- Comprehensive Cost-to-Complete Audit: A line-by-line itemization comparing original contractor estimates with current expenditures, remaining contract balances, and pending change orders.
- Architect & Engineer Certification: Signed inspections confirming actual physical percentage completion and certifying that proposed modifications comply with municipal building codes.
- Updated Draw Schedule & Cash Flow Forecast: An adjusted timeline of anticipated funding requests across remaining construction phases, reflecting revised delivery dates.
- Lien Waiver Documentation: Executed conditional and unconditional partial lien waivers from all general contractors, primary trades, and material suppliers to date.
- Contingency Allocation Record: An accounting breakdown showing utilized hard-cost and soft-cost contingencies alongside remaining unallocated reserves.
- Updated Title Endorsements: Updated title searches verifying that no mechanic’s liens or junior encumbrances have attached to the subject real estate.
Reader Action Plan: Navigating Project Pivots
If your active commercial build is experiencing budget shifts, subcontractor delays, or scope alterations, taking structured operational steps protects both your development schedule and investor relationships:
- Step 1: Quantify the Deviation Early: Avoid absorbing change orders out of general operating cash. Quantify hard costs, soft costs, and schedule impacts within 5 business days of identifying scope revisions.
- Step 2: Review Existing Loan Covenants: Identify mandatory notification thresholds, rebalancing provisions, and default triggers outlined in your current credit agreement.
- Step 3: Conduct a Draw Schedule Audit: Evaluate whether your current interest reserve and undisbursed loan balance can sustain the project through revised completion milestones.
- Step 4: Engage Capital Advisors: Consult with commercial debt specialists to model adaptive financing structures, including loan upsizing, mezzanine facilities, or mid-project refinances.
- Step 5: Execute Structured Loan Amendments: Finalize modified draw protocols, expanded facilities, or takeout financing commitments before existing contingency budgets are depleted.
Frequently Asked Questions
What is adaptive construction financing?
Adaptive construction financing refers to flexible commercial loan structures designed to accommodate changes in project scope, schedule delays, and cost overruns through modified draw schedules, dynamic interest reserves, and structured contingency funding.
How does mid-project refinancing work?
Mid-project refinancing involves replacing or restructuring an existing construction debt facility while construction is actively underway. This provides additional capital to cover expanded build scopes, lowers carry costs, or lengthens the loan term to accommodate extended delivery dates.
How do flexible draw schedules benefit commercial builders?
Flexible draw schedules align disbursements with actual construction progress and physical milestone completion rather than arbitrary calendar dates. This structure ensures contractors receive prompt payment for completed phases, preventing costly site shutdowns and trade disputes.
What triggers an interest reserve shortfall during construction?
An interest reserve shortfall occurs when construction delays extend the build duration past the original completion schedule, or when benchmark interest rates elevate carrying costs beyond initial calculations. Adaptive loan structures resolve this by recapitalizing interest reserves or allowing dynamic debt service adjustments.