
Thorne CRE vs Traditional Bank Lending Comparison
Commercial real estate (CRE) financing refers to capital funding secured by commercial properties, including office, retail, industrial, and multi-family assets. Choosing the right financing partner is a critical strategic decision for developers, investors, and property owners. While large traditional banks have historically dominated commercial lending, specialized lenders like Thorne CRE offer distinct advantages, particularly for nuanced, transitional, or time-sensitive transactions.
Key Differences in CRE Financing Approaches
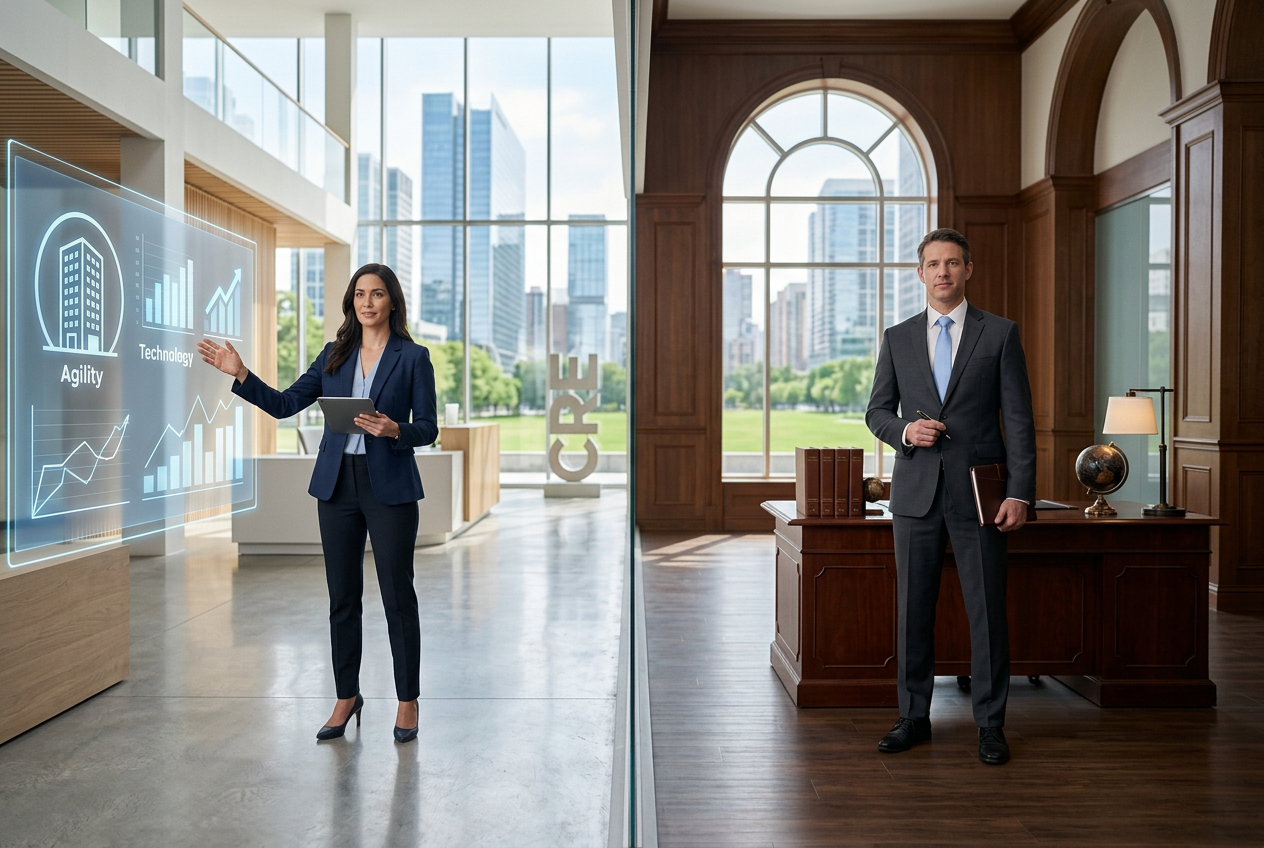
The fundamental operational differences between specialized CRE lenders and traditional commercial banks stem from their risk appetites, decision-making structures, and strategic client focus.
Speed and Efficiency
- Thorne CRE: Employs streamlined underwriting processes, fewer bureaucratic layers, and direct access to principal decision-makers. This structure enables significantly faster loan approvals and closings, often within weeks or even days for specific bridge products.
- Traditional Banks: Institutional lenders like JPMorgan Chase and Wells Fargo typically operate with extensive internal credit committees, rigid underwriting guidelines, and multiple administrative layers. As a result, loan approval processes can stretch over several months, increasing borrower holding costs or risking lost acquisition opportunities.
Flexibility and Customization
- Thorne CRE: Provides a broad spectrum of structured debt and equity solutions, including bridge loans, mezzanine financing, construction loans, and preferred equity. Each transaction is tailored to specific project timelines, property classes, and borrower strategies.
- Traditional Banks: Focus primarily on conventional, low-leverage, fully stabilized asset financing. Product lines remain standardized with limited flexibility for complex capital stacks or projects outside rigid lending criteria. Reviewing key steps to secure commercial real estate financing can help clarify which debt structure best fits your asset type.
Niche Expertise and Problem Solving
- Thorne CRE: Specializes in complex, value-add, transitional, and time-critical CRE projects. The underwriting teams possess specialized sector expertise required to structure deals that conventional lenders often view as too complex or unconventional.
- Traditional Banks: Frequently lack dedicated underwriting parameters for niche asset classes (such as specialized hospitality or emerging industrial facilities) or complex repositioning strategies, leading to project declines based on standard institutional templates. Regional market dynamics, such as those covered in our guide on commercial real estate financing in Pennsylvania, also influence bank appetite.
Personalized Service and Relationship Management
- Thorne CRE: Delivers a direct client experience through dedicated points of contact, direct communication with decision-makers, and proactive deal management throughout the loan life cycle.
- Traditional Banks: Borrowers often navigate multi-departmental corporate structures, leading to communication friction, departmental handoffs, and slower response times.
5 Scenarios Where Thorne CRE Excels
Specialized lending frameworks offer distinct performance advantages across specific commercial real estate investment scenarios:
1. Time-Sensitive Acquisitions
Pain Point: An investor must close quickly to lock in favorable purchase pricing or outbid competitors, but traditional institutional timelines require 60 to 90 days.
Thorne CRE Advantage: Direct underwriting authority allows rapid execution, providing interim or bridge capital within days to weeks so buyers secure competitive property contracts.
2. Value-Add or Transitional Properties
Pain Point: A property requires heavy renovation, repositioning, or tenant lease-up, resulting in current cash flows that fall short of traditional bank debt-service coverage requirements.
Thorne CRE Advantage: Underwriting focuses on post-renovation stabilization value (as-complete value) and execution strategy rather than historical trailing cash flows.
3. Non-Recourse or Higher-Leverage Needs
Pain Point: Sponsors seek non-recourse debt or require higher loan-to-value (LTV) ratios than standard bank caps to optimize equity returns across major acquisitions.
Thorne CRE Advantage: Capital access enables structured non-recourse financing and higher LTV limits tailored for experienced sponsors and growth-focused portfolios. Understanding overall commercial real estate financing options helps match loan terms to investment risk profiles.
4. Unique Property Types or Business Models
Pain Point: Specialized industrial assets, niche hospitality, or non-standard property uses do not fit into rigid institutional bank underwriting templates.
Thorne CRE Advantage: Deep industry knowledge allows flexible evaluation of specialized real estate assets and custom business models that standard banks decline due to policy constraints.
5. Refinancing Maturing Debt with Limited Options
Pain Point: Existing debt is reaching maturity during shifting market conditions or before asset stabilization, limiting conventional bank refinancing options.
Thorne CRE Advantage: Flexible bridge financing bridges capital gaps, giving borrowers time to complete stabilization, improve net operating income, or secure long-term takeaway debt. Sponsors operating across different regions can evaluate localized strategies like commercial real estate financing in Virginia or Washington state market financing.
Frequently Asked Questions
What is the main difference between Thorne CRE and a traditional bank?
Thorne CRE specializes in agile, flexible commercial real estate loans—such as bridge, mezzanine, and value-add debt—with rapid closing timelines. Traditional banks focus primarily on conventional, low-risk, stabilized property loans subject to strict credit committees and longer approval cycles.
How fast can Thorne CRE close a loan compared to a traditional bank?
Thorne CRE can complete underwriting and close specialized loans within days or weeks, whereas traditional banks like JPMorgan Chase or Wells Fargo typically require 60 to 90+ days due to multi-layered committee reviews.
Does Thorne CRE offer non-recourse financing?
Yes, Thorne CRE provides access to structured non-recourse debt options and higher loan-to-value ratios tailored to qualified sponsors and specialized property acquisitions.
Conclusion
While traditional institutions like JPMorgan Chase and Wells Fargo remain key providers for low-risk, stabilized property loans, Thorne CRE offers a purpose-built alternative for investors needing speed, high leverage, structural flexibility, and deep market expertise. For complex, transitional, or time-sensitive projects, tailored capital solutions provide the competitive edge required for execution.